

This article first appeared in Capital, The Edge Malaysia Weekly on October 6, 2025 - October 12, 2025
THE local bourse, which has seen strong momentum in recent weeks, is expected to see rotational plays in construction and utility stocks in the fourth quarter of this year (4Q2025), as analysts expect these sectors to benefit from budget allocations and upcoming jobs for data centres, gas power plants and battery storage.
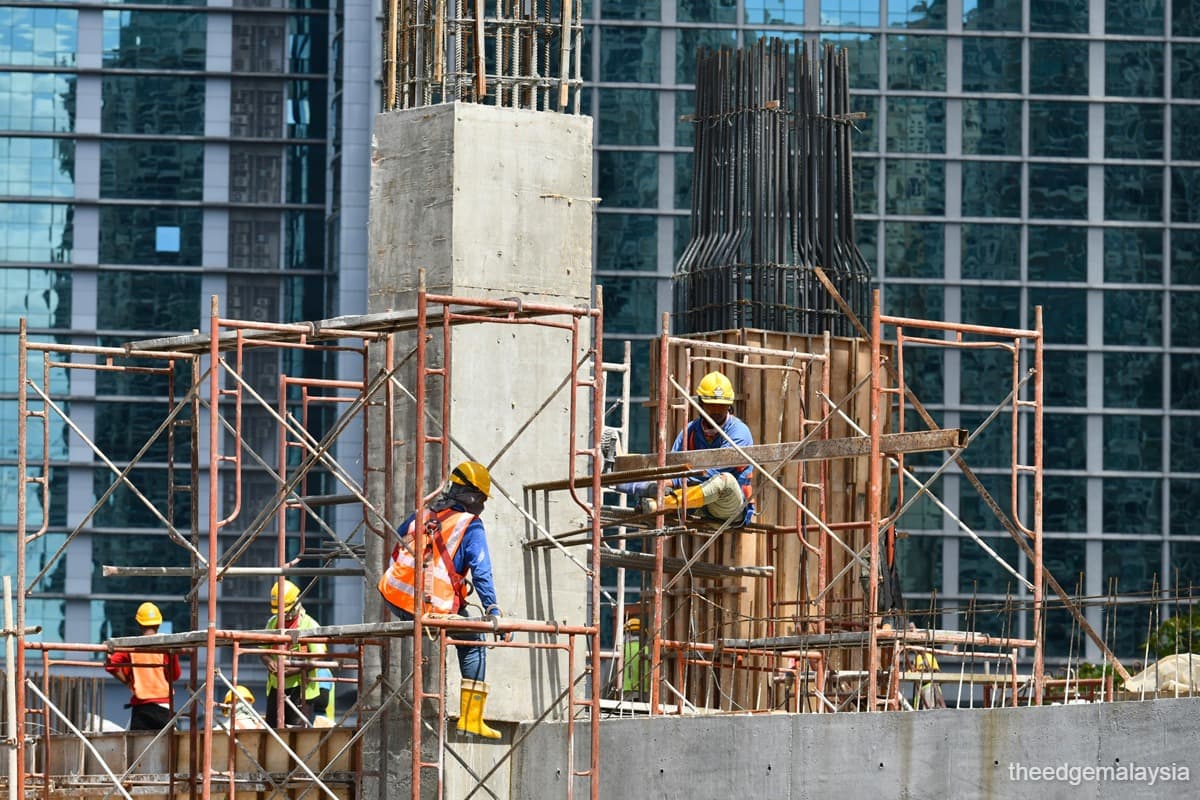
The tabling of Budget 2026 on Oct 10 is expected to boost interest in construction counters, especially with development spending under the 13th Malaysia Plan and the possible revival of the Mass Rapid Transit Line 3 (MRT3) project.
Meanwhile, household spending — reinforced by budget allocations such as the lower RON95 pump price for locals and the RM2.2 billion Sumbangan Asas Rahmah (Sara) programme — could lift consumer plays. In addition, tourism-linked counters, riding on the early momentum for Visit Malaysia 2026, offer another bright spot.
Analysts and fund managers whom The Edge spoke to concur that selected plays on the bourse could be propped up by relatively undemanding valuations and the prospect of foreign buying as the ringgit strengthens.
“With expectations of further US interest rate cuts, we expect the US dollar to weaken against other currencies, including the ringgit. The prospects of declining US dollar interest rates and weakening currency, and moderating US economic growth, may encourage some Wall Street investors to redirect their funds to countries/regions with more stable interest rates and higher growth vis-à-vis the US economy,” MBSB Investment Bank head of research Imran Yassin Yusof tells The Edge.

“In this regard, we expect Malaysia to be able to attract some of the redirected funds, as Bank Negara Malaysia is expected to keep the overnight policy rate (OPR) unchanged for the foreseeable future. Second, Malaysia is estimated to register relatively higher economic growth. In 4Q2025, we expect pent-up buying from the return inflow of foreign funds to help drive the local equity market higher.”
According to MBSB’s fund flow report for the week ended Sept 26, foreign investors turned net sellers with a net outflow of RM451.5 million, ending two weeks of purchases.
“The top three sectors that recorded net foreign inflows were consumer products and services (RM127 million), plantation (RM61.2 million) and energy (RM49.4 million). The top three sectors that recorded net foreign outflows were financial services (-RM241.1 million), utility (-RM177.7 million) and healthcare (-RM137.2 million). Meanwhile, local institutions reversed to net buying activity, ending a two-week consecutive net selling streak and registering a net inflow of RM696 million,” said the research house.
AmInvestment Bank head of equity research Paul Yap Ee Xing believes the construction sector will see sustained interest, as more data centre jobs are expected to be awarded, lifting order books for key players. “For the power sector, we expect news flow related to the winners of the battery and new gas power plant tenders,” he notes.
MBSB Research’s Imran is positive on the consumer sector, underpinned by resilient macro fundamentals, targeted policy support and structural growth drivers. “Universal cash aid, subsidised fuel, deferred toll hikes and wage enhancements, and the 25bps OPR cut [by Bank Negara on July 9] continue to reinforce household disposable income and support spending across both staples and discretionary categories.
“Meanwhile, labour market conditions remain firm. In addition, tourism recovery adds a further uplift, boosting retail, F&B and convenience demand ahead of Visit Malaysia 2026.
“On the cost side, softer inputs, alongside a firmer ringgit, should alleviate margin pressures, offsetting the impact of the expanded sales and service tax and higher crude palm oil costs. Overall, the combination of demand resilience, policy tailwinds and easing cost pressures provides a constructive backdrop for earnings visibility, positioning the sector to deliver resilient performance going into 4Q2025 and beyond.”
MBSB Research has Fraser & Neave Holdings Bhd (KL:F&N), AEON Co (M) Bhd (KL:AEON) and Life Water Bhd (KL:LWSABAH) as its top picks for the sector, with target prices of RM32.08, RM1.77 and RM1.11 respectively. It downgraded Spritzer Bhd (KL:SPRITZER), Nestlé (Malaysia) Bhd (KL:NESTLE) and Oriental Kopi Holdings Bhd (KL:KOPI) to a “sell”, following their recent share price rally.
“Discretionary/sin items in the consumer sector may be hit as the government rolls out the planned expansion of the pro-health tax to include tobacco, vape and alcohol. This will shift consumption patterns, causing demand to fall as higher taxes raise prices,” cautions AmInvestment Bank’s Yap, whose top pick in the consumer sector is 99 Speed Mart Retail Holdings Bhd (KL:99SMART), with a target price of RM2.90.

Most sectors disappointed in 9M2025, tech and finance could stage turnaround in 4Q
On Sept 30, the FBM KLCI stood at 1,611.88 points, having dipped 1.85% in the first nine months of this year (9M2025). Most market experts are maintaining their year-end target for the benchmark index in the range of 1,640 to 1,660 points (see table).
Year to date, Bursa Malaysia’s Construction Index and Utilities Index rose 7.53% and 1.3% respectively, while a good majority of the other indices sank during the period (see charts).

The heads of research concur that the healthcare sector has underperformed the most so far this year, owing to the disappointing performance of glove stocks, which are “still beset by sectoral issues such as intense competition”. In 9M2025, the sectoral index tumbled 34% to a multi-year low of 1,583.42 points.
AmInvestment Bank’s Yap and MBSB Research’s Imran believe the healthcare sector may not see any meaningful turnaround this year as glovemakers continue to face structural oversupply and intense competition from Chinese producers expanding into Southeast Asia.
Nonetheless, Kenanga Research has turned bullish on the tech sector, as tariff-related exposure seems to be contained and the sector is a prime beneficiary of the dissipating of tariff-related risks. “Amid the global semiconductor sales momentum proving to be sustained, we prefer the visibility of wafer fab expenditure, which benefits front-end exposed players such as Kelington Group Bhd (KL:KGB) (TP: RM6.15)and UWC Bhd (KL:UWC) (TP: RM3.82),” it says.
“Inari Amertron Bhd (KL:INARI) (TP: RM2.56) rounds off our top three tech picks, given its leverage to capex-led growth and rising relevance in AI applications. We are also more comfortable with the exposure to automotive, given rosier prospects in key markets of China, Europe and the US, which in turn would improve the broader automotive semiconductor and LED ecosystem.
“D&O Green Technologies Bhd (KL:D&O) (TP: RM1.61) would be well placed to ride this recovery. However, one of the risks here would be a strong ringgit, where the tech sector would conversely be exposed to a larger negative impact.”
Meanwhile, MBSB Research’s Imran foresees that the banking sector could stage a turnaround in 4Q2025. Reiterating its “positive” call on the sector, MBSB in its Oct 1 monthly sector report said the sector remains resilient with “extremely attractive dividend yields despite headwinds”.
“We believe the sector’s fundamental outlook remains sound, with robust earnings (even after factoring in net interest margin compression), manageable asset quality, large-scale recoveries and better loan growth expected in the months ahead,” said MBSB, which lists RHB Bank Bhd (KL:RHBBANK) and Hong Leong Bank Bhd (KL:HLBANK) as its top picks for the sector, with target prices of RM7.21 and RM21.71 respectively.
Similarly, Kenanga Research is bullish on the banking sector, noting that the recent OPR cut could improve demand for new loans even if it also leads to further weakness in deposits.

“Seasonal year-end offerings could lead deposits to end on a relatively stronger note. We have yet to see meaningful strains arising from the implementation of the US tariffs in August, with industry GIL (gross impaired loans) still remaining solid at 1.43% during the month,” said Kenanga in its Oct 1 sectoral update, in which it highlighted AMMB Holdings Bhd (KL:AMBANK) (TP: RM6.90) as a top pick in the sector for its return-on-equity optimisation efforts and higher dividend yield prospects of about 6%.
The research house also sees Hong Leong Bank (TP: RM24.50) as a long-term investment, thanks to its “leading asset quality”, and likes Malayan Banking Bhd (KL:MAYBANK) (TP: RM11.30) for its current price points, leading market share, better-than-industry gross impaired loans and dividend yield of about 6%.
In the small-cap space, Kenanga Research has its eye on Samaiden Group Bhd (KL:SAMAIDEN) for its significantly higher earnings potential from expected job wins in FY2026 and FY2027. It has raised its TP by 30% to RM2.08, from RM1.60.
In TA Securities’ 4Q2025 Market Outlook report, head of research Kaladher Govindan articulated that Malaysian equities offer a compelling risk-reward profile going into 4Q2025 and 2026, underpinned by supportive domestic policy momentum, historically low foreign positioning and a more favourable global liquidity backdrop.
While geopolitical risks warrant selectivity, the combination of low foreign ownership, supportive fiscal policy and sector-specific growth drivers positions Malaysia as a relative outperformer among its Asean peers in 2026, he said.
“Foreign shareholding in Malaysian securities stood at 18.7% as at September 2025, near the 2003 trough of 18.1%, suggesting significant rerating potential if sentiment turns. Any downside pressure is likely to be cushioned by sustained net buying from domestic institutional funds, which have absorbed RM16.4 billion in year-to-date foreign outflows,” said Govindan, who advocated exposure to unvalued blue chips, domestic construction and property, defensive plays and high-growth small caps, for exposure and navigation of uncertainties.
TA Securities maintains its year-end FBM KLCI target of 1,660 points, based on 14.5 times 2026 earnings.
For investors, the window of opportunity in 4Q2025 may be in positioning early in banking, construction and consumer counters before broader flows lift valuations higher going into 2026.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.