

This article first appeared in Wealth, The Edge Malaysia Weekly on August 25, 2025 - August 31, 2025
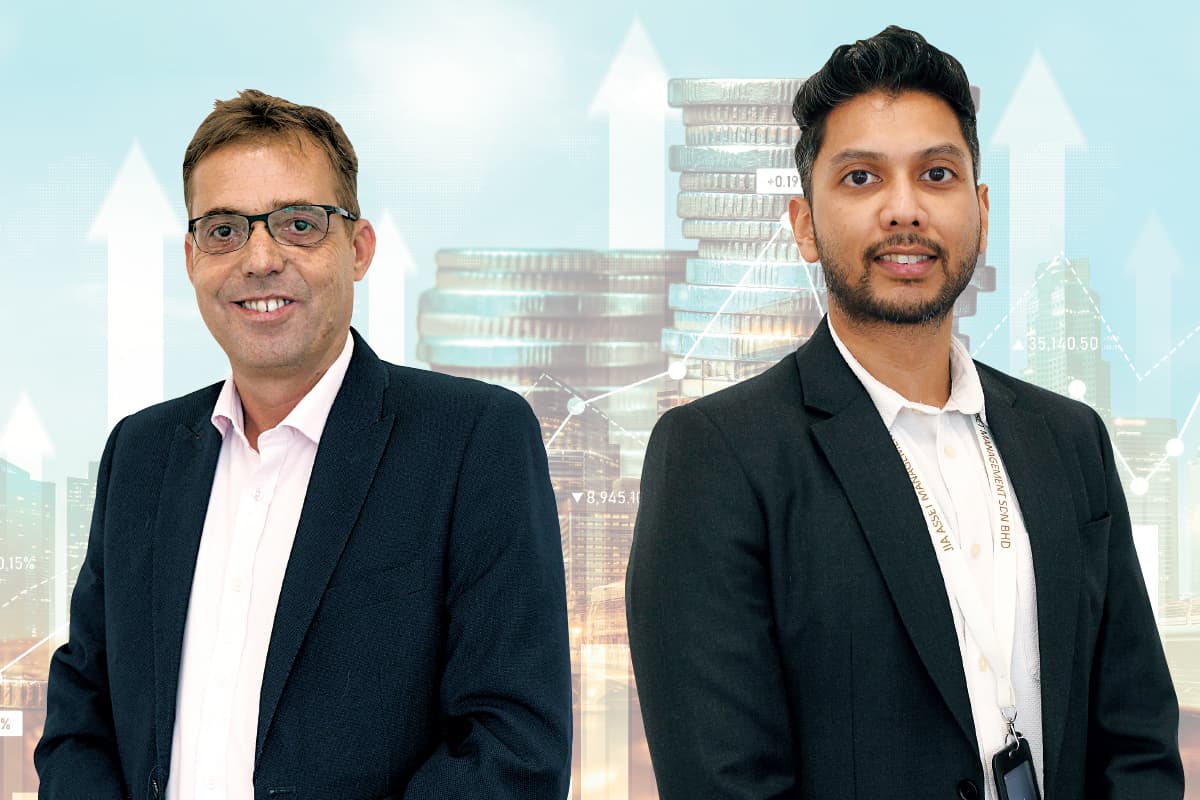
A seasoned private banker and luxury watch lover, Emmanuel Burdet is also the founder and CEO of boutique fund house JIA Asset Management Sdn Bhd. Three years after it was licensed by the Securities Commission Malaysia, the firm has garnered close to RM100 million in assets under management (AUM) and is aiming for more, partly by offering alternative investment products.
A Swiss national, Burdet says he is one of the few — if not the first — foreigners to apply for a boutique fund management licence in Malaysia. The country isn’t the friendliest or cheapest destination in the region to set up a fund house, but Burdet has cultivated personal relationships with local clients, whom he wishes to serve, and aims to gradually grow his base.
Prior to setting up JIA, Burdet was a relationship manager at Swiss banks Credit Suisse (now merged into UBS), Piguet Galland & Cie SA and Julius Baer for over 13 years. He was based in Singapore during his employment with Julius Baer, and subsequently joined Lumen Capital Investors, a multi-family office and asset management firm, as its chief representative officer in Jakarta and Malaysia, serving local clients for more than seven years.
“I always keep my relationship with my clients wherever I move to. I have a close relationship with them because I don’t sell them products, but solutions that help meet their goals,” says Burdet during an interview with Wealth.
His investment solution is often conservative where capital preservation comes before capital gains.

“I don’t want to show my clients the statement and say, ‘Excuse me, Mr so-and-so, your return performance is minus 10%.’ I would rather deliver 1% now and outperform the market over the long term. That’s my philosophy and the way I work with my clients,” he adds.
Winning clients is all about trust and being honest is important, says Burdet. As a wealth manager, it often means conveying key information to clients without sugar-coating and admitting mistakes when they are made.
“Transparency is the key. If you try to hide things, such as fees and performance, as in how much a product actually costs and its actual return, you lose clients. But if you tell them the reality, by being transparent, the relationship will work. It’s exactly like your relationship with your wife,” he quips.
His down-to-earth character might have also helped him make friends easily in Asia. Burdet says the Swiss tend to be perceived as “proud” people who enjoy the finer things in life, including luxury watches, food, champagne and sports cars. Some of them, especially private bankers who want to show that they share a common interest with high-net-worth individuals, like to display their collections or preferences to the public. But Burdet says this is not necessary.
When asked, Burdet describes himself as being “more traditional” and “low-key”.
“When you’re young, you want to show off a bit here and there. But as I age, I think it’s better to be low-key. Even if you have assets and money, just keep it to yourself.
“I don’t think it’s necessary to connect with clients through luxurious hobbies. What is important is your reputation in the market and your character. Ultimately, nobody cares if you’re driving a sports car or having the best watches.
“I love watches. I’m a member of the Malaysia Watch Club. Coming from Switzerland, watches are everywhere. But I don’t need to show off my collection [to win over clients],” he says.
Burdet’s client network and personal character seem to have served the firm well. But the progress JIA has made is also thanks to the collective effort of other key personnel of the firm.
Sitting on its board as chairman is Datuk Dr Sharifuddin Abdul Wahab, former regional managing director of biomedical firm Schmidt Southeast Asia and former CEO of Schmidt BioMedTech Asia Ltd. He is currently president director of Jakarta-based insurer PT KSK Insurance Indonesia, according to its official website.
Datuk Dominic Silva, former head of investments and executive director at Khazanah Nasional Bhd, is JIA’s senior adviser while Benjamin Pedly, former regional chief investment officer of HSBC Private Bank, based in Hong Kong, is its head of strategy.
Joel Brown, previously a senior product specialist at AHAM Asset Management Bhd’s wealth and advisory department, is JIA’s fund manager and director.
Based on the firm’s CTOS report, Burdet and Sharifuddin each hold a 37.5% stake in JIA. Director Katijah Rosli has a 4.97% stake, while the rest of the equity interest is held by JIA Asset Management Pte Ltd (20.02%). The latter is a licensed asset manager in Singapore with a capital markets services licence issued by the Monetary Authority of Singapore in April 2018, according to its official website.

Access to global solutions, Swiss banks and Australian properties
So, what is the value proposition of JIA that will allow the firm to make its mark on the local asset management industry? After all, Burdet’s long-term goal is to become one of the top 10 fund houses in Malaysia in terms of AUM.
Burdet says JIA has established a partnership with Bank of Singapore (BOS), a wholly-owned subsidiary of Oversea-Chinese Banking Corp (OCBC) and a provider of private banking services. JIA’s clients can tap a variety of services provided by BOS, including its suite of investment products, loans, credit cards and other financing facilities.
“We can use their facilities, which, in turn, make us a provider of global [financial services] while also providing local products,” he adds.
Burdet is also leveraging his career experience as a Swiss banker for over a decade to provide JIA’s clients with access to products and services offered by Swiss private banks, with which he has established a relationship over the years.
He clarifies that providing access to Swiss banks does not mean helping its high-net-worth clients to “hide” their funds overseas, but to offer them estate planning and trust services as well as a destination to diversify their assets amid market uncertainties.
Burdet says high-net-worth individuals who have assets regionally or globally are increasingly worried about the heightening geopolitical tensions, with some preferring to park part of their wealth in Switzerland and in Swiss franc, which is widely regarded as one of the safe-haven assets during uncertain times apart from the US dollar and Singapore dollar. The country also has a solid and stable financial system.
The trust services provided by Swiss private banks are also sought after by JIA’s local clients, including Muslim clients who want to distribute their wealth for estate planning purposes or in case of divorce.
“When a client approaches me for such services, I’m the relationship manager for that, which means the client contacts me and I will link them up with professionals from the Swiss private banks for meetings and discussion.
“Some discussions may be private. It’s between the trustee and the client, which I don’t need to know. But the paperwork and other processes, we will settle them and ensure they are all in order while complying with the regulations,” says Burdet.
“All this means we are offering different global solutions, not just selling products. That’s also why our clients are happy to pay us a management fee [for their funds managed by us]. Why should they pay us the fee if we provide the same solutions as the local banks, right?”
Burdet also wants to present JIA’s clients with creative products and investment opportunities that suit their financial needs, instead of competing with established local asset management firms in an already crowded space such as Malaysian fixed income and equities.
That is why the firm launched its Australia Income Fund in May, aiming to provide local investors with steady and attractive monthly income, says Brown.
“Malaysians generally have quite a high affinity for Australia as many send their children there for further studies, but there aren’t many Australia-based products in the market. That’s kind of how we went about it by analysing the market. Then we try to find the best partner to work with,” he adds.
The Australia Income Fund is a feeder fund that injects investors’ capital into the MA Secured Loan Series, managed by MA Investment Management Pty Ltd, an Australian Securities Exchange-listed private credit asset manager.
Brown says the Australia Income Fund aims to provide investors with returns of the Reserve Bank of Australia (RBA) rate plus 4%. Based on an RBA rate of 3.6% as at Aug 15, this means the fund is targeting to provide investors with an annual return of 7.6%. The income it generates is distributed every month — a main draw for investors who are looking for steady cash returns.
Private credit is essentially a loan, Brown explains. The Australia Income Fund generates returns by providing loans to property companies in the form of senior secured bonds, which are mostly short-term debt that hold the highest priority in repayment in the event of liquidation.
These bonds are also backed by properties, which would be sold in the event of default and the proceeds used to repay the investors.
“To protect our investors, the fund managers have taken one step further by lowering the loan-to-value ratio to 55% to 60%, which means that when the borrower can’t make the repayment, the property backing the loan will need to drop by over 40% in value before investors start losing money,” says Brown.
He adds that these loans are also short term, with the average tenure ranging from nine to 12 months. The longest tenure is 36 months.
“Typically, property developers pledge their residual units as collateral to take on these short-term loans that the fund provides. They may sell 60% to 70% of their units, and use the remaining 30% to 40% to secure loans for cash.
“These opportunities are rather unique to the Australian market as their financial industry is very concentrated on banks, making it harder for businesses to borrow money. The non-banking institutions step in nicely to provide these short-term property or construction loans for returns,” says Brown.
The key risk for the fund is liquidity, as properties cannot be sold quickly in the event of default. When many people rush in for redemption, some may not be able to withdraw their funds quickly or in full.
However, there have only been nine such instances since 2017 when the fund manager had to sell properties to repay investors, and without them taking on any losses, says Brown.
Other than liquidity risk, the fund is taking on interest rate risk as the loans are negotiated based on the RBA rate plus a spread. If the RBA lowers its rates, the returns for investors are also going to fall.
The health of the Australian property market is vital to the fund.
“Of course, there is also the risk of fund managers failing to value properties correctly or negotiate for proper terms for the loans, which is not dissimilar to other investment products,” says Brown.
Private credit opportunities in the local market
On the local front, JIA launched its Energy Transition Fund that targets to provide investors with 8% return per annum, distributed semi-annually. It is a wholesale fund with a minimum investment amount of RM10,000 and charges investors a subscription fee of 2% and annual management fee of 1.8%.
The private credit fund has a lock-in period of five years, which may be extended for up to two more years. It is in the process of conducting due diligence on five solar energy projects — three in Malaysia and two in the region, according to Brown.
Meanwhile, in August last year, JIA announced a strategic partnership with venture capital firm Vynn Capital to become a limited partner in the Vynn Capital Progression Fund that focuses on mobility and supply chain-related investment opportunities.
JIA currently holds a boutique asset management firm licence under the Securities Commission, which only allows it to accept 50 investors as clients, says Burdet. Given the good traction it has gained so far, he is looking to apply for a full-fledged licence that does not come with a cap on the number of investors it can accept.
Burdet has an ambitious goal that he intends to achieve in the next five years, which is to hit RM1 billion in AUM.
Commenting on this, Brown says the firm intends to accomplish this partly by continuing to offer creative products that are relevant to Malaysians.
“I think we can say with confidence that we will not come up with the same old products already in the market. We always try to innovate and look for new areas that give us an opportunity. Obviously, we are still small in size, which makes us nimble,” he continues.
Brown says the world has moved past the phase of “easy money” seen during the Covid-19 pandemic, when most risk assets performed exceptionally well, making it easier for investors to generate good returns. Things have changed drastically now, mainly due to geopolitical tensions, causing fund managers to be a lot more selective in their investments.
He points out that investors are also increasingly adding alternative asset classes in their portfolio as the negative correlation between equity and bond has not been working as well in recent years, leaving fund managers with few options to achieve positive performance. This is why alternative asset classes such as private credit or gold, whose prices do not correlate as much with equity and bond, are becoming more popular these days.
“Globally, I think the trend is to start including a bit more funds in alternative asset classes, on top of your portfolio that includes traditional asset classes like equities and bonds. This is an area that we are focusing on,” says Brown.
The jury is still out on whether JIA can expand further to become a force to be reckoned with in the local asset management scene. But Burdet expresses his confidence: “Time will tell. We are still new in the market. But we will definitely be the little brother you have to keep an eye on.”
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.