

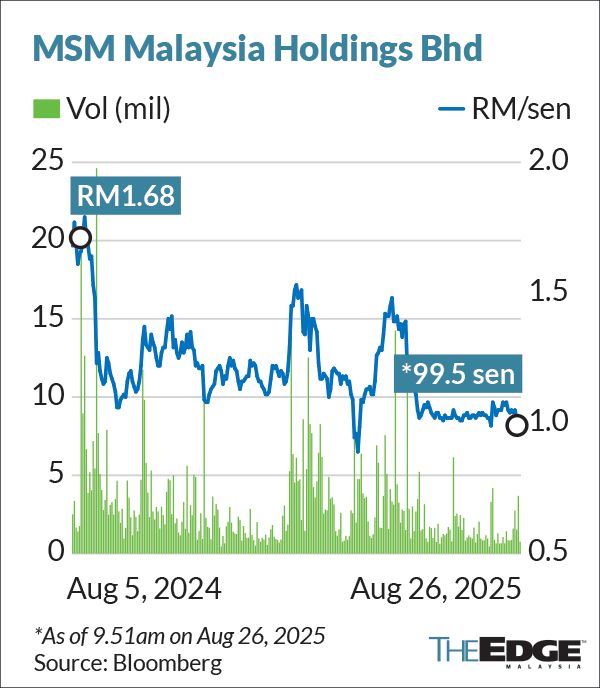
KUALA LUMPUR (Aug 26): Shares of MSM Malaysia Holdings Bhd (KL:MSM) slipped on Tuesday after analysts downgraded the stock to ‘sell’, amid weaker-than-expected results and a cloudy outlook weighed down by the risk of Thai sugar dumping following China’s ban on liquid sugar imports.
BIMB Securities Research, one of only two research houses covering the counter, cut its rating to ‘sell’ after MSM reported a core net profit of RM7.1 million for the first half ended June 30, 2025 (1HFY2025).
This was after factoring in a net realisable value adjustment and onerous provision of RM22 million, which left earnings at just 29% of its full-year forecast — below expectations.
The research house also slashed its earnings projections by 48% for FY2025 (ending Dec 31), 68% for FY2026 and 72% for FY2027, reflecting expectations of weaker average selling prices (ASPs) and thinner margins ahead.
“In the near to medium term, we remain cautious on MSM’s prospects given the uncertainty surrounding Thai sugar dumping following China’s ban on liquid sugar imports, which could further pressure ASPs.
"This is compounded by bearish NY11 prices amid abundant supply from the top three raw sugar producers. Furthermore, foreign exchange fluctuations remain a potential risk to earnings,” said BIMB in a note on Tuesday.
Shares of MSM — the sugar arm of FGV Holdings Bhd (KL:FGV) and one of only two sugar refiners in the country — slipped 1.5% to 98 sen at the time of writing on Tuesday. Year to date, the counter has fallen over 19%.
The other refiner is unlisted Central Sugars Refinery Sdn Bhd, which is controlled by Tan Sri Syed Mokhtar Al-Bukhary's Perspective Lane (M) Sdn Bhd.
In a separate note, MBSB Research, which also downgraded the stock to 'sell' from 'neutral', expects MSM’s recovery to be delayed, projecting a turnaround only from next year instead of FY2025.
It warned that weaker demand, an influx of Thai sugar, and a narrowing ASP premium in both the industrial and export segments would continue to weigh on earnings.
“We are taking a more conservative stance against competitive price war between the AP (approved permit) players that probably still have inventory to carry forward over the next two years,” it added, pegging a lower target price of 71 sen on MSM.