

This article first appeared in The Edge Malaysia Weekly on July 28, 2025 - August 3, 2025
IJM Corp Bhd (KL:IJM) and AFA Prime Bhd — the latter being the concession holder for the KL-Karak Highway and East Coast Expressway Phase 1 — are in the running to acquire Permodalan Nasional Bhd’s (PNB) highway assets, sources privy to the matter tell The Edge.
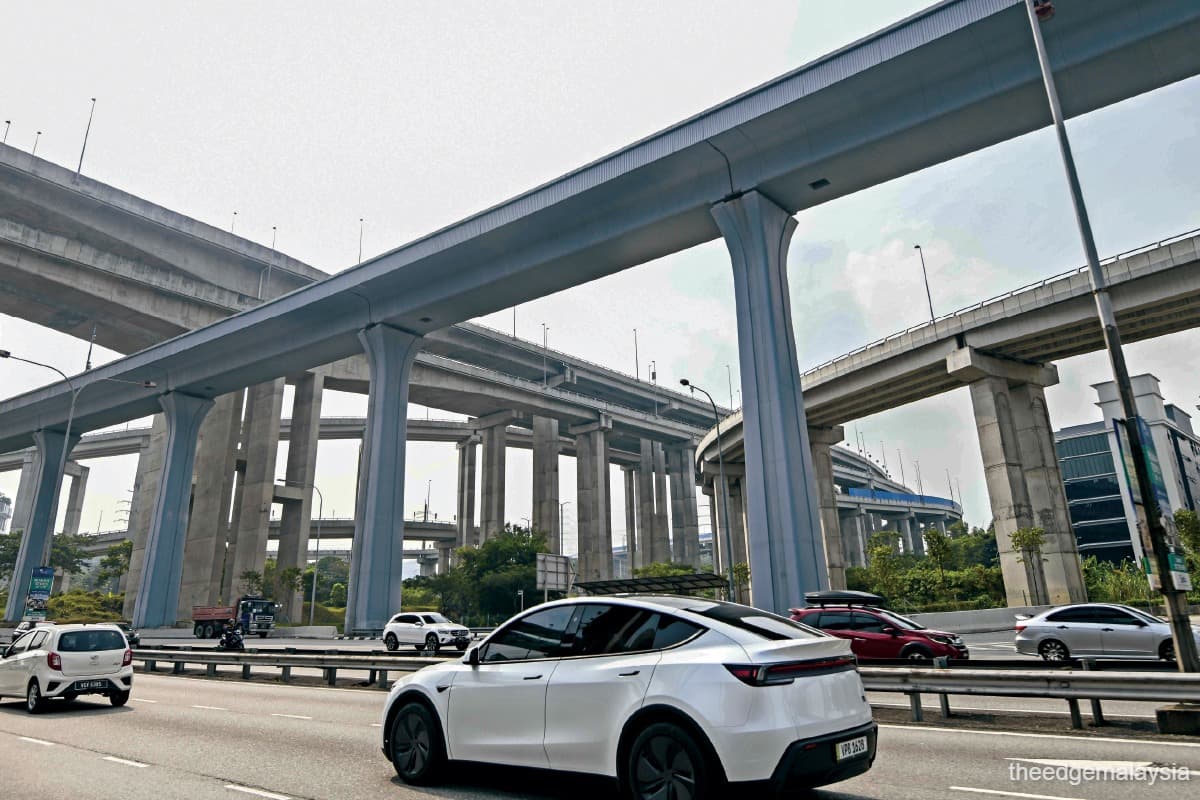
PNB is said to be looking to dispose of its two highways held under Projek Lintasan Kota Holdings Sdn Bhd (Prolintas), which owns the concessionaires for the Sungai Besi-Ulu Kelang Expressway (SUKE) as well as the Damansara-Shah Alam Highway (DASH), and 51% in Prolintas Infra Business Trust (KL:PLINTAS), the highway asset trust listed on Bursa Malaysia. Prolintas Infra BT holds the concessions for four urban highways — the Ampang–Kuala Lumpur Elevated Highway (AKLEH), the Guthrie Corridor Expressway (GCE), the Kajang Dispersal Link Expressway (Kajang SILK) and Lebuhraya Kemuning Shah Alam (LKSA).
A few of the smaller companies under Prolintas, such as Prolintas Highway Services Sdn Bhd, Prolintas Managers Sdn Bhd and Prolintas Corporate Shared Services Sdn Bhd are also understood to be in the mix.
In a statement to The Edge, PNB confirms that it is undertaking a strategic option evaluation exercise on its stake in the Prolintas group, encompassing the exploration of several options, including retaining ownership of the asset or bringing in a strategic partner.
“The exercise is still at a very preliminary stage and no decision has been made on this matter. PNB understands and is committed to its core mandate and all decisions are guided by a rigorous governance process aligned with our objectives,” the government-linked investment company says.
However, The Edge understands that the bids for PNB’s highways closed late last week, and although a couple of funds had expressed interest at the outset of the process, only two bids were received — from IJM and AFA Prime.
In a brief phone conversation with The Edge, Tan Sri Azmil Khalili Khalid, who controls AFA Prime and formerly helmed MTD Group, reiterates what he had said in February this year in an interview. “I’m on the lookout for brownfield toll road concessions.”
IJM, in response to email questions says, “As a business, we regularly evaluate opportunities that are aligned with our long-term strategy. We review them as part of our normal course of business. At this point, there is nothing further to disclose.”
The sale is likely to be challenging.
Not a straightforward sale
The sale of the 51% block will likely trigger a mandatory general offer (MGO) for Prolintas Infra BT. At its close of 97.5 sen per share last Thursday, Prolintas Infra BT had a market capitalisation of RM1.07 billion.
Other notable shareholders in Prolintas Infra BT include the Employees Provident Fund, which has a 7.58% stake, the Ministry of Finance’s Urusharta Jamaah Sdn Bhd with 5.78% and pilgrim fund Lembaga Tabung Haji with 5.45%. Interestingly, PNB, via Prolintas and its various funds, controls 60.74% of Prolintas Infra BT.
There is also the issue of pricing and ultimately funding. It is understood that the valuation being bandied about for the acquisition of PNB’s highway assets is around RM3 billion.
At 97.5 sen apiece, 51% of Prolintas Infra BT has a market value of RM545.7 million. Depending on the offer price for Prolintas, the same price will then have to be extended for the remaining shares in Prolintas Infra BT.
PNB’s confirmation of looking into several options for its stake in Prolintas is set to raise eyebrows as it has only been 16 months since the listing of Prolintas Infra BT in March 2024. The infra business trust was listed at 95 sen apiece, raising RM445.3 million for PNB through Prolintas.
It is not expected to be a straightforward acquisition. Apart from the need for the acquirer to offer to buy the remaining units in Prolintas Infra BT, there could also be complications in regards to an Islamic financing done prior to the initial public offering.
According to Prolintas Infra BT’s prospectus, the Islamic financing of up to RM2.7 billion was raised by Prolintas Managers on behalf of the trust to refinance the existing debt of the concession companies as well as fund capital expenditure for the construction of a new interchange on the GCE and lane widening on SILK.
The financing was provided by Bank Pembangunan Malaysia Bhd (BPMB). It has a tenure of 24 years from the date of the first disbursement. Prolintas Managers entered into the financing agreement on Dec 11, 2023.
Under the terms of the Islamic financing, Prolintas, PNB, any unit trust fund managed by PNB and/or its subsidiary, shall at all times throughout the tenure of the facility hold in aggregate more than 33% of all units of Prolintas Infra BT in issue.
BPMB may declare a default if Prolintas Managers transfers or disposes of, or threatens to transfer or dispose of, a substantial part of its business or assets and the result of any of the foregoing may, in the opinion of the bank, adversely affect the trustee-manager’s financial condition or its ability to observe or perform its obligations under the facility agreement.
It is not clear if PNB and BPMB have sorted out this shareholding arrangement.
RM3 bil price tag for Prolintas
Considering that Prolintas has an undertaking with BPMB, including PNB and its unit trust funds, to continue to hold an aggregate of 33% of Prolintas Infra BT, the potential acquirer may have to take over the entire debt of the business trust.
As at March 31, 2025, Prolintas Infra BT’s total borrowings stood at RM2.34 billion, being the outstanding amount of the Islamic financing scheme. With cash reserves of RM492.1 million as at March 31, 2025, the enterprise value (EV) of Prolintas Infra BT amounted to RM2.84 billion. This means that the EV of Prolintas Infra BT alone is almost RM3 billion. This does not take into account the value of SUKE and DASH, which are held directly by Prolintas.
“The indicative value of RM3 billion, if referring to the enterprise value, calculated as debt plus equity minus cash, is a fair estimate. Any prospective investor will likely be guided by the EV target expected by PNB.
“However, if the RM3 billion refers to equity value, it would be overly ambitious, given that Prolintas Infra BT’s current market capitalisation is only RM1 billion … Unless, of course, the RM3 billion equity valuation expectation also includes other highways currently owned by PNB, namely DASH and SUKE, which are not part of the Prolintas Business Trust,” says Datin Wong Muh Rong of Astramina Advisory Sdn Bhd, a licensed corporate finance advisory firm.
Prolintas’ issued share capital as at Feb 7, 2024, (latest practicable date of Prolintas Infra BT’s prospectus) was RM3.46 billion, comprising 1.57 billion ordinary shares and 1.88 billion preference shares.
Meanwhile, Prolintas Infra BT’s total equity and liabilities as at March 31, 2025 stood at RM3.65 billion.
Prolintas had also raised debt facilities to finance the development of SUKE and DASH in the past.
Projek Lintasan Sungai Besi-Ulu Klang Sdn Bhd (PLSUKE), the wholly-owned subsidiary of Prolintas which operates SUKE, has total outstanding sukuk of RM2 billion expiring on Nov 26, 2027.
SUKE is a 24.4km toll road running from Sri Petaling to Ulu Kelang under a 55-year concession agreement (CA) that ends in December 2069 (with a conditional extension for another 10 years).
Meanwhile, Projek Lintasan Damansara-Shah Alam Sdn Bhd, the concessionaire of DASH, has total non-current liabilities of RM4.7 billion. In 2018, the concessionaire raised RM2.5 billion in construction bridge Islamic term financing for the development of the elevated highway which connects Puncak Perdana in Shah Alam to the Penchala Interchange in Damansara, a distance of 20.1km.
The concession for DASH will also end in December 2069.
Acquiring the Prolintas group would create a larger toll highway concessions group for either IJM or AFA Prime.
Acquiring the Prolintas group would give AFA Prime a substantial footprint in the Klang Valley urban highway sector.
The independent market research report provided by Frost & Sullivan for the listing of Prolintas Infra BT states that the four highways it operates captured a market share of 14.9% of the total industry revenue based on its toll revenue in 2021.
The total market size based on the revenue of the concessionaires for the urban highways in the Klang Valley was estimated at RM2.3 billion in 2021.
In addition, Prolintas Infra BT’s total traffic volume in 2021 of 109.3 million was about 15.7% of the total highway traffic volume in the Klang Valley in the same year, notes Frost & Sullivan.
If IJM manages to acquire the Prolintas group, it would enlarge its highway concessions assets, which are already some of the major urban highways in the Klang Valley.
IJM owns Besraya (M) Sdn Bhd, the concessionaire of the Sungai Besi Expressway, New Pantai Expressway Sdn Bhd and Lebuhraya Kajang-Seremban Sdn Bhd, and has a 28.12% stake in WCE Holdings Bhd (KL:WCEHB).
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.