

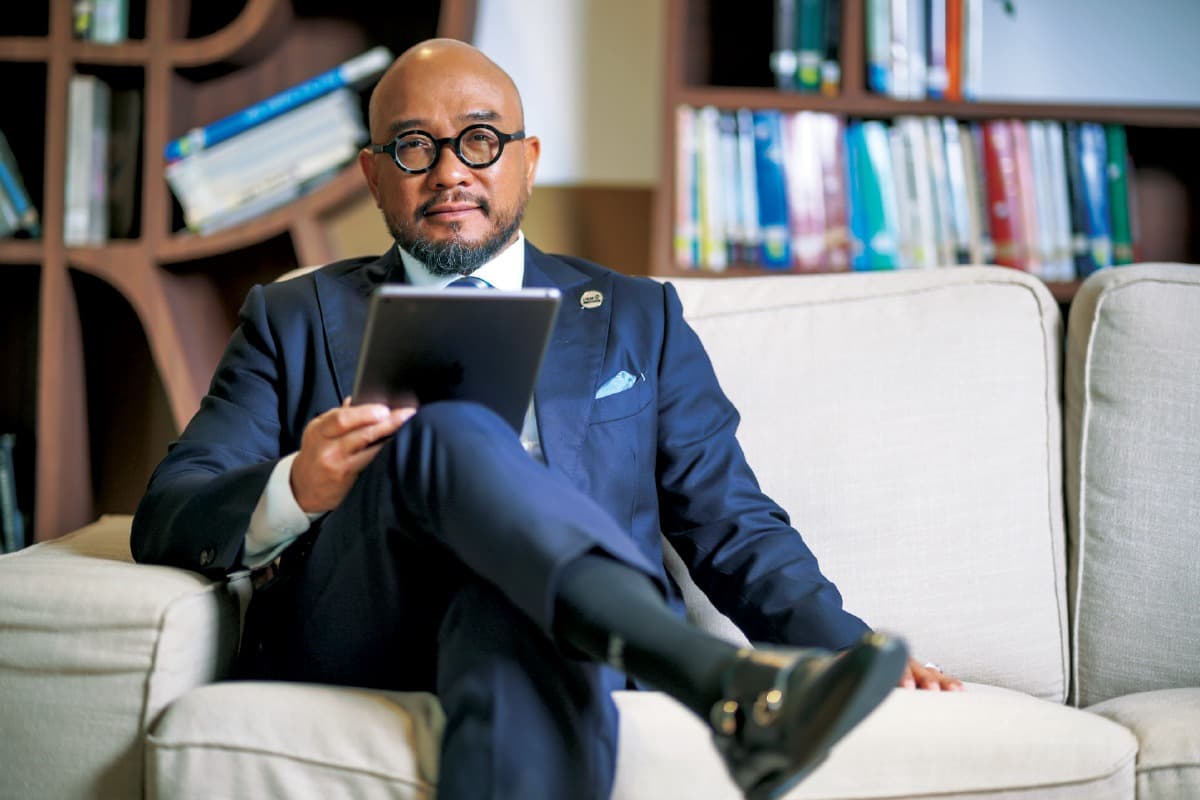
This article first appeared in The Edge Malaysia Weekly on June 16, 2025 - June 22, 2025
UEM Edgenta Bhd (KL:EDGENTA) took more than a decade to significantly establish its overseas business. The asset management and infrastructure solutions firm’s expansion began when it bought KFM Holdings for RM128 million in 2015, which grew its footprint to the United Arab Emirates (UAE).
Today, the group has a presence in the UAE, Saudi Arabia, Singapore and Taiwan, where it has a large number of tenders in the pipeline. In fact, in the financial year 2024 (FY2024), about 75% of its RM2.8 billion in new contract wins were from its overseas ventures.
From what UEM Edgenta managing director and CEO Syahrunizam Samsudin says, the company’s ventures in Dubai, the UAE, could pay off significantly. Last week, the group entered into a joint venture (JV) with Dubai-based 21 Estates FZCO to provide property management services for master developments in Dubai, properties located in or owned by Expo City Dubai (ECD), as well as selected sites globally.
While the group did not specify the potential value of the JV, Syahrunizam highlights the increased demand for property management services in Dubai. “We are looking at 10 to 20 years’ growth potential in Dubai by going into this JV,” he tells The Edge in an exclusive interview, as the city is seeing large-scale construction and real estate developments.
“The ECD is located in the southern part of Dubai and is expected to be the next growth area, especially with the upcoming airport there. We are also raising our profile locally by having an overseas presence.”

UEM Edgenta’s entry into the Middle East’s premium property management sector began with its acquisition of Kaizen from NW Kaizen Holdings Ltd for about RM55 million in February last year.
Syahrunizam says the new JV with 21 Estates will further enhance UEM Edgenta’s footprint in the UAE, by providing an integrated real estate services platform designed for the UAE and potentially other regional markets.
The JV is expected to be finalised by the third quarter of this year and is expected to positively contribute to UEM Edgenta’s future financial performance.
Overseas expansion crucial
The overseas segment is crucial for UEM Edgenta, especially with local jobs, which already have razor-thin margins, slowing down.
Its strong balance sheet of RM473.62 million cash puts the group in a strong position to bid for overseas jobs and potentially undertake mergers and acquisitions (M&A). The M&A could be in Singapore, where it has established a foothold.
In April, UEM Edgenta was awarded contracts worth S$220.48 million (RM729.66 million) by ALPS Pte Ltd to provide hospital support services in Singapore. The contracts are for between 32 months and five years, starting from May 1, 2025.
The group’s order book currently stands at RM9 billion, with 80% being Malaysian projects and 20% from overseas. Despite this lopsided geographical split, Syahrunizam says revenue contribution from local and international operations is about equal.
“Also, we generate higher margins from overseas jobs — around 12% to 18% in Singapore, Dubai and Taiwan — compared with about 10% in the Malaysian market,” he adds. Against this backdrop, the company has set a five-year target to secure 60% of its order book overseas and 40% locally.
Syahrunizam says the group is looking at M&A potential, especially in Singapore, to ramp up its overseas expansion. It is already in negotiations for a few potential M&A across the Causeway, he adds.
“The areas we are looking at are integrated facilities management and hospitality. Today, many hotels are outsourcing these services. We currently manage the concierge for Marina Bay Financial Centre in Singapore,” he says.
The group is not new to M&A in the city state. In 2016, it acquired Singapore-based Asia Integrated Facility Solutions Pte Ltd — a well-established facilities management provider with more than 25 years of experience — for S$185.9 million. The company services more than 90 hospitals and healthcare institutions in Singapore, Taiwan and Malaysia.
With overseas growth accelerating, UEM Edgenta is now considering a dual listing in Singapore or even a separate listing of its international business.
“This is still at the internal discussion stage. But if we want to expand further overseas, especially in Singapore, it’s an option we are seriously considering,” says Syahrunizam.
“From there, we can grow regionally. In Singapore, UEM Edgenta is already seen as an international company. We’re competing with top players and the standards are high.”
Weak financials spark privatisation talk
Considering that a chunk of UEM Edgenta’s contracts are long-term concessions, Syahrunizam says investors should look at the long-term potential of the company, and not focus on the recent losses suffered.
The group fell into the red in 1QFY2025, recording a net loss of RM17.95 million, compared with a net profit of RM9.77 million a year earlier. The loss was attributed to higher operating costs and cyclical factors.
Syahrunizam describes the recent weakness in the group’s financial results as “a blip” and expects stronger quarterly performance for the remainder of FY2025, driven by its overseas projects.
The last time the company posted a net loss was in 3QFY2020, due to pandemic-related disruptions in its infrastructure business and inventory impairments.
“We are confident that the group will do better from 2QFY2025 onwards. We expect to achieve at least a similar earnings level as FY2024, or better,” he says.
Nevertheless, UEM Edgenta’s disappointing financial performance has again sparked speculation about a potential privatisation.
Syahrunizam brushes aside talk of the weak financials being engineered to enable a cheap privatisation. The speculation has been further fuelled by the sharp decline in its share price following the release of its 1QFY2025 results. The counter fell 18% to 74 sen per share on June 11, from 91 sen on May 23. It should be noted that this is not the first time the possibility of a privatisation has emerged.
Syahrunizam opines that UEM Edgenta is undervalued at the current trading levels. Nevertheless, he believes that a privatisation exercise is unlikely. He says such a decision would rest with the major shareholders — UEM Group Bhd and sovereign wealth fund Khazanah Nasional Bhd. UEM Group controls a 69.14% stake, followed by Urusharta Jamaah Sdn Bhd 5.75% and Employees Provident Fund 2.48%.
“If you look at the intrinsic value of the share price, we should be trading at least at RM1.10 a share. The group’s net assets per share is RM1.88,” Syahrunizam points out.
“Also, the group secured close to RM1 billion worth of contracts in Singapore and Taiwan in the first quarter of this year. This shows we have been aggressively winning jobs abroad.”
RHB Research, which recently ceased coverage on UEM Edgenta, has recommended a “buy” call on the counter, with a target price of RM1.04 per share, which is almost 30% higher than the last traded price of 74 sen.
In a May 28 report, the research house said UEM Edgenta’s 1QFY2025 results came in below expectations, dragged down by a decline in the healthcare support division due to a contract termination in Malaysia, lower contribution from its infrastructure services segment and higher manpower expenses due to the minimum wage hike.
When asked about the contract termination, Syahrunizam points out that the annual revenue contribution from the non-core contract is about RM35 million. “We recognised a one-off gain of RM10.15 million from the termination. While this had some impact on 1Q results, we do not expect it to materially affect our performance in the coming quarters,” he says.
“In fact, we are seeing strong growth momentum in healthcare internationally — with new wins of RM462.8 million in Singapore and RM328.7 million in Taiwan — which will more than offset this. The healthcare segment remains a key pillar of our business going forward.”
When asked about UEM Edgenta’s receivables, which stood at RM677 million as at 1QFY2025, Syahrunizam says the group is continuously working on improving its collection. However, as some of its clients — both local and overseas — are in the public sector, the collection cycle is “slightly longer”.
“We have made good progress — our days sales outstanding (DSO) improved to 80.2 days from around 95.7 days in the previous quarter. We continue to actively manage receivables through tighter internal processes and close client engagement. Importantly, we do not see any material credit risk arising from this,” he says.

Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.