

This article first appeared in Capital, The Edge Malaysia Weekly on June 2, 2025 - June 8, 2025
MALAYSIAN consumers’ love of convenience stores has certainly grown. In 2024, the retail sales of the mini-market, convenience store and cooperative subsector made it the best performing retail subsector of the year, expanding 8.5%, according to data compiled by Retail Group Malaysia.
Granted, that subsegment would likely include the bigger retail chains such as 99 Speed Mart Retail Holdings Bhd (KL:99SMART), MR D.I.Y. Group (M) Bhd (KL:MRDIY) and even newly listed Eco-Shop Marketing Bhd (KL:ECOSHOP).
Nevertheless, the proliferation of convenience stores in the country, especially in the Klang Valley, has certainly cranked up the heat on this segment of the retail industry.
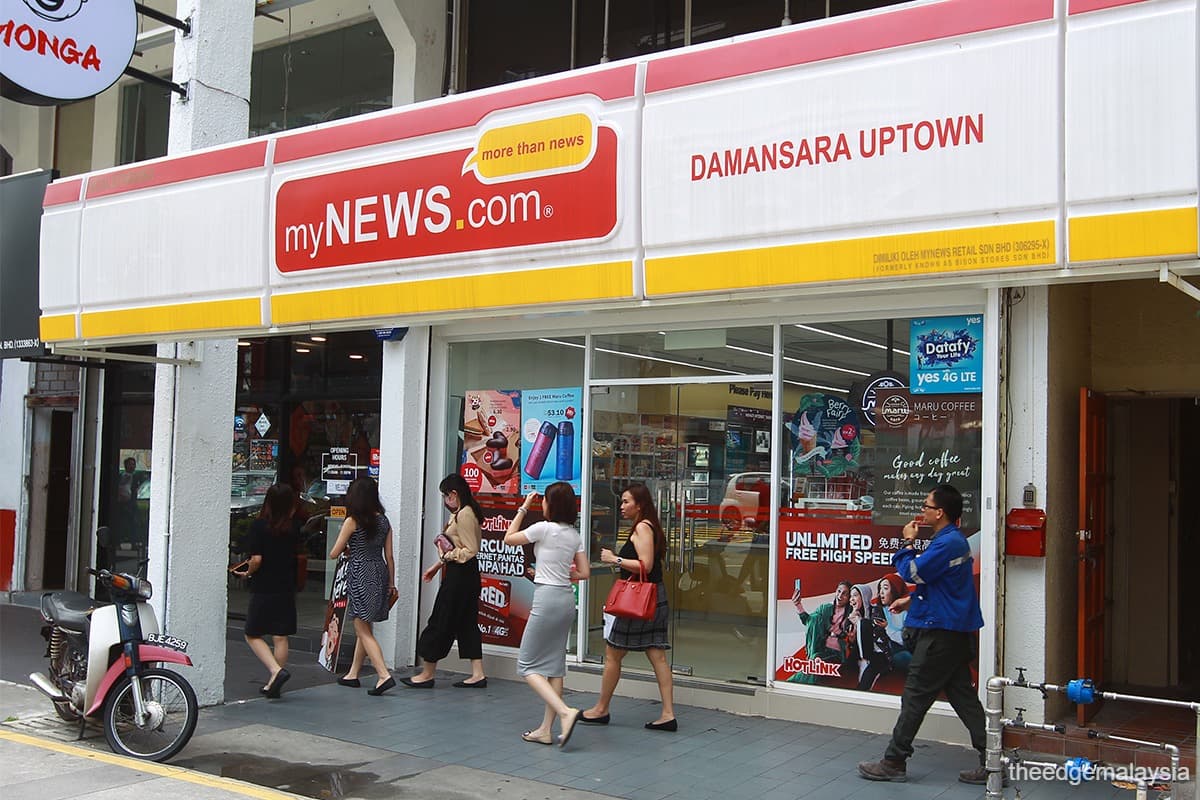
With existing players such as 7-Eleven Malaysia Holdings Bhd (KL:SEM), MyNews Holdings Bhd (KL:MYNEWS) and FamilyMart under QL Resources Bhd (KL:QL) fighting to keep their brand foremost in the mind of consumers to expand market share, newer unlisted players like BilaBila Mart, MiX Store and emart24 have to work harder for a slice of the pie, each leveraging their own unique selling proposition.
Some quarters project a softening in consumer sentiment this year on the back of higher costs, given potential subsidy reforms, the expanded sales and service tax plus tariff concerns, which would ultimately lead to tighter purse strings.

Recent business tendency statistics released by the Department of Statistics Malaysia, measuring businesses’ expectation of performance for the next three and six months, revealed on a sector basis that sentiment in the wholesale and retail trade sector indicates pessimism, with the confidence indicator contracting 6.7% in the second quarter (2Q2025). Still, this is an improvement from a contraction of 8.1% in 1QFY2025.
Can the convenience store segment go against the flow as spending softens?
“Convenience stores now stock a wide variety of ready-to-eat (RTE) meals. They are quite popular among consumers these days. They could benefit from consumer ‘downtrading’ where instead of dining in restaurants, they might choose an RTE meal from the convenience store,” says Rakuten Trade head of equity sales Vincent Lau.
Maybank Investment Bank Research (Maybank IB Research) estimates that 7-Eleven derives about 14% of its group sales from its 7CAFé outlets. The convenience store chain added the 7CAFé outlet concept to its portfolio in 2021, and is looking to continue expanding the network of stores in order to increase its higher-margin fresh food sales contribution.
When 7-Eleven disposed of its stake in Caring Pharmacy for RM675 million in 2023, about 60% of the amount was earmarked to be utilised for its 7CAFé store expansion. Its focus on expanding the 7CAFé outlets showed how consumer preferences for RTE meals and fresh food had evolved.
Notably, FamilyMart and MyNews have also introduced standalone café outlets as part of their portfolios — FamilyMart with its FamiCafé brand in 2022 and Maru Kafe for MyNews in 2024.
MyNews’ CU brand, a South Korean convenience store, derives about 50% of its sales from fresh food offerings while its myNews outlets derive less than 20% of sales from fresh food.
MyNews executive chairman Dang Tai Luk is cognisant of how consumer spending could be affected by rising costs, which is why the home-grown convenience store chain is looking to introduce value meals and to continuously improve efficiency to reduce costs. The group will also tap its cross brands Mynews loyalty app to grow and retain its customer base to mitigate any impact.
“The impact of cost increases will be across the whole retail industry and we believe that customers are opting for essential items and groceries over non-essentials. Moreover, we are dealing in small-value items,” he says in a reply to The Edge, implying that the convenience store sector could be the least impacted compared to other segments of retail.
Others concur as they assert that demand for products at the convenience store is inelastic.
“Many would still continue to buy their packet of cigarettes or continue picking up their RTE meals from convenience stores when costs increase. Cigarette demand is inelastic while RTE meals are inexpensive,” notes an observer.

How do they stack up?
Among the three convenience stores listed on Bursa Malaysia, 7-Eleven has the widest network with a total of 2,646 outlets as at March 31, 2025. MyNews and FamilyMart are closer in numbers as MyNews boasted a total 632 outlets as at Jan 31, 2025 while FamilyMart’s is estimated at some 445 outlets as at March 31, 2025.
However, in terms of revenue generated per store, FamilyMart generated the highest amount at RM2.7 million per outlet in its financial year ended March 31, 2024 (FY2024) while MyNews came in second at RM1.26 million for its financial year ended Oct 31, 2024. 7-Eleven’s revenue per store for the financial year ended Dec 31, 2024 amounted to RM1.11 million.

FamilyMart has been growing its profit before tax sequentially over the last five years, except for a blip in FY2021, when profit before tax (PBT) was lower at RM12.56 million, compared with RM17.97 million in FY2020.
But as QL Resources’ financial year ends on March 31, the financial performance for FY2021 would have reflected the full impact of the movement control order during the Covid-19 pandemic.
Following the blip in FY2021, FamilyMart’s PBT rebounded significantly to RM43 million in FY2022, an increase of over three times the previous year’s.
For FY2025, FamilyMart’s PBT amounted to RM62.3 million against revenue of RM1.21 billion.
FamilyMart’s PBT margins have improved over the last five financial years. In FY2020, PBT margins amounted to 4%. Although it dipped to 2.5% in FY2021 before rebounding to 6.7% in FY2022, it has stabilised at around the 5% range since FY2023.

While 7-Eleven is the largest convenience store chain of the three names, analysts do not appear to be keen on it. Bloomberg data shows that the stock has two “hold” recommendations and two “sell” calls but no “buy” call, with an average target price of RM1.62.
In the first quarter ended March 31, 2025, 7-Eleven recorded a net profit of RM10.63 million against revenue of RM755.28 million. Revenue increased by 10.3% from a year earlier as same-store sales growth increased by 7.1% but net profit was 17.1% lower for the same period. Earnings were bogged down by higher selling and distribution costs, the increase in minimum wage and higher interest expense.
Maybank IB Research, in a May 29 report, says that while it focuses on growing its 7CAFé stores, which should shore up margins eventually, it believes that the operating cost in relation to its expansion plans may outpace sales growth in the near term.
CGS International, which has a “hold” call on the stock, comments in its May 29 report that 1Q2025 net margins were lower at 1.4% due to lower fresh food sales because of the fasting month which, in turn, affected net profit.
“We expect fresh food sales to recover in subsequent quarters of 2025F, which would lead to a strong rebound in profits,” it says.
Looking over the five-year period and excluding its earnings from Caring Pharmacy, profit from the convenience store segment has been uneven. Between FY2020 and FY2024, profit ranged between RM98.7 million (in FY2021) and RM137.6 million (in FY2022). In FY2024, profit amounted to RM135.5 million.
Interestingly, profit margin for the convenience store segment was the highest in FY2021 and FY2022, at around 5.5%, before trending downwards to 4.4% in FY2023. It subsequently ticked upwards slightly to 4.6% in FY2024.
CIMB Research has a “reduce” call on the stock, with a target price of RM1.63. It is of the view that the stock’s current valuation of 33 times CY2026F price-earnings ratio (PER) is steep on account of intensifying competition in the convenience store landscape and rising cost pressures.
7-Eleven’s trailing 12-month PER amounts to 52.5 times and has an average forward 12-month PER of 33.39 times according to Bloomberg estimates. It closed at RM1.97 last Thursday, unchanged from the beginning of the year.
In contrast, analysts are bullish on MyNews with six “buy” calls and one “hold” call, with an average target price of 84 sen.
The more bullish outlook stems from MyNews’ better performance, emerging from a rut in FY2024 to post a net profit of RM8.71 million against revenue of RM804.2 million. The convenience store chain had felt the full brunt of the pandemic. It was in the red for four years since FY2020, as its food processing centre (FPC), which commenced operations just before the pandemic hit, bled while its rapid expansion of South Korea’s franchise CU outlets proved to be more challenging to break even than expected.
However, it seems to have got over the bump, with the CU franchise and the FPC seeing better days.
“CU is Ebitda (earnings before interest, taxes, depreciation and amortisation)-positive. Even though it is yet to break even to date, partly due to seasonal impact such as Ramadan, its losses have narrowed substantially,” Dang shares.
He adds that the average basket size ranges between RM11 and RM15 for the MyNews group, with CU’s average basket size higher than myNews outlets.
As for its FPC, CGS International says, in a March 27 report, after the release of the company’s 1QFY2025 financials, that it has managed to stay profitable for three consecutive quarters — a first since the commencement of operations in 2019.
“We believe that improvements in its FPC utilisation were due to better consumer demand for its food products. In our view, the FPC’s performance should continue to improve in subsequent quarters as we project a pickup in consumption and consumer spending in FY2025F,” says the research house. It has an “add” call on the stock, with a target price of RM1.18.
For 1QFY2025, MyNews reported revenue of RM215.87 million while net profit amounted to RM3.87 million.
Maybank IB Research, which has a “buy” call and a target price of 80 sen, opines that the outlook remains positive for MyNews.
“Sequential earnings are expected to improve on stronger consumer spending from the minimum wage hike (effective Feb 1, 2025), which, in turn, should partially mitigate its labour cost impact on FY2025 earnings,” it says in its March 27 report.
MyNews’ trailing 12-month PER stands at 35.1 times. It has a forward 12-month PER of 18.6 times according to Bloomberg data. Last Thursday, it closed at 56 sen, lower by 17.6% year to date.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.