

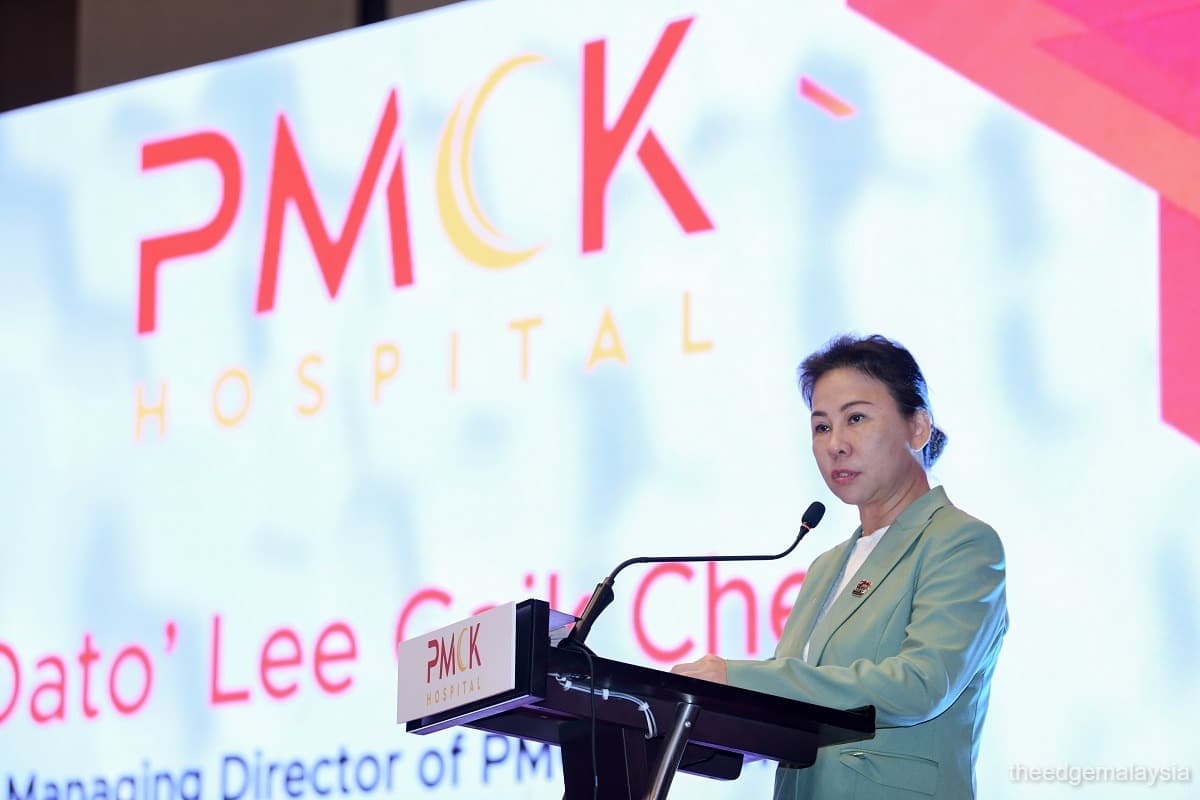
KUALA LUMPUR (May 26): Kedah-based private healthcare provider PMCK Bhd, which is en route to list on the ACE Market of Bursa Malaysia, said an implementation of diagnostic-related fixed healthcare payment would benefit its operations due to its competitive pricing currently.
Speaking at a press conference after PMCK's prospectus launch, PMCK managing director Datuk Lee Gaik Cheng said the company’s pricing remains below the ceiling set by current government regulations, which cap the maximum chargeable fees for medical services at private hospitals.
"Our business model sits between public and premium hospitals," said Lee, adding that the company aims to maintain a pricing strategy that ensures profitability while remaining affordable for customers.
Malaysia's healthcare industry is currently exploring the diagnosis-related group (DRG) system as a means to control medical inflation in the country.
The DRG system categorises patients based on classifications of diagnoses and procedures. The patients are charged fixed rates based on those classifications, regardless of final cost of treatment.
However, implementation at private sector hospitals will not happen anytime soon, The Edge reported, quoting sources.
Nonetheless, it will be piloted in selected public hospitals, which will help the government better track cost efficiency of each hospital based on each product (treatment type), and allow better budget allocation across hospitals.
If it is expanded to the private sector, private hospitals will have to charge for medical services based on pricing that is established by the government. Since PMCK currently charges below the price cap for a service, it would benefit when DRG is implemented because it has to raise its pricing to meet DRG's threshold, PMCK financial controller Yap Chee Yoong explained.
If the DRG system is implemented in the future, it could benefit the company by boosting its gross profit margin from 35.5% in FY2024, as the company would be able to charge higher medical fees instead of the current rates that are below the ceiling price, said Malacca Securities corporate finance vice-president Tan Sin Jiang at the press conference.
PMCK, which runs a medical centre as well as dental and polyclinics, is seeking to raise RM59.97 million, partly to fund its ongoing expansion.
It is now developing a RM193 million facility dubbed PMC Kulim, consisting of a 12-storey private medical centre, food court and hotel that will prioritise patients’ family members on a site measuring over 141,000 square feet in Kedah.
PMC Kulim will add 90 beds to the company’s current 121 beds, with operations expected to commence in the first quarter of 2028.
PMC Kulim will also introduce a new in vitro fertilisation (IVF) service, also known as test tube baby, as there is currently “no one” offering this service in Kulim, said Lee when asked about the reason for the addition.
Despite current market volatility, Lim expressed confidence that PMCK will achieve full subscription for its initial public offering (IPO).
Although the current market is weak, "we are very confident that PMCK shares will be fully subscribed. We have received a lot of interest from institutional investors and many others, so we are very confident of full subscription", Malacca Securities co-head of corporate finance Law Kim Fatt added.
The IPO values PMCK at 15.94 times earnings for the financial year ended April 30, 2024 (FY2024), which Law deemed as "fair". This compares with its peers such as KPJ Healthcare Bhd (KL:KPJ) (35.8 times trailing 12 months PER), IHH Healthcare Bhd (KL:IHH)(22.9 times), Cengild Medical Bhd (KL:CENGILD) (18.1 times) and eye specialist Optimax Holdings Bhd (KL:OPTIMAX) (22.3 times) based on their share prices on May 23.