

This article first appeared in Capital, The Edge Malaysia Weekly on January 20, 2025 - January 26, 2025
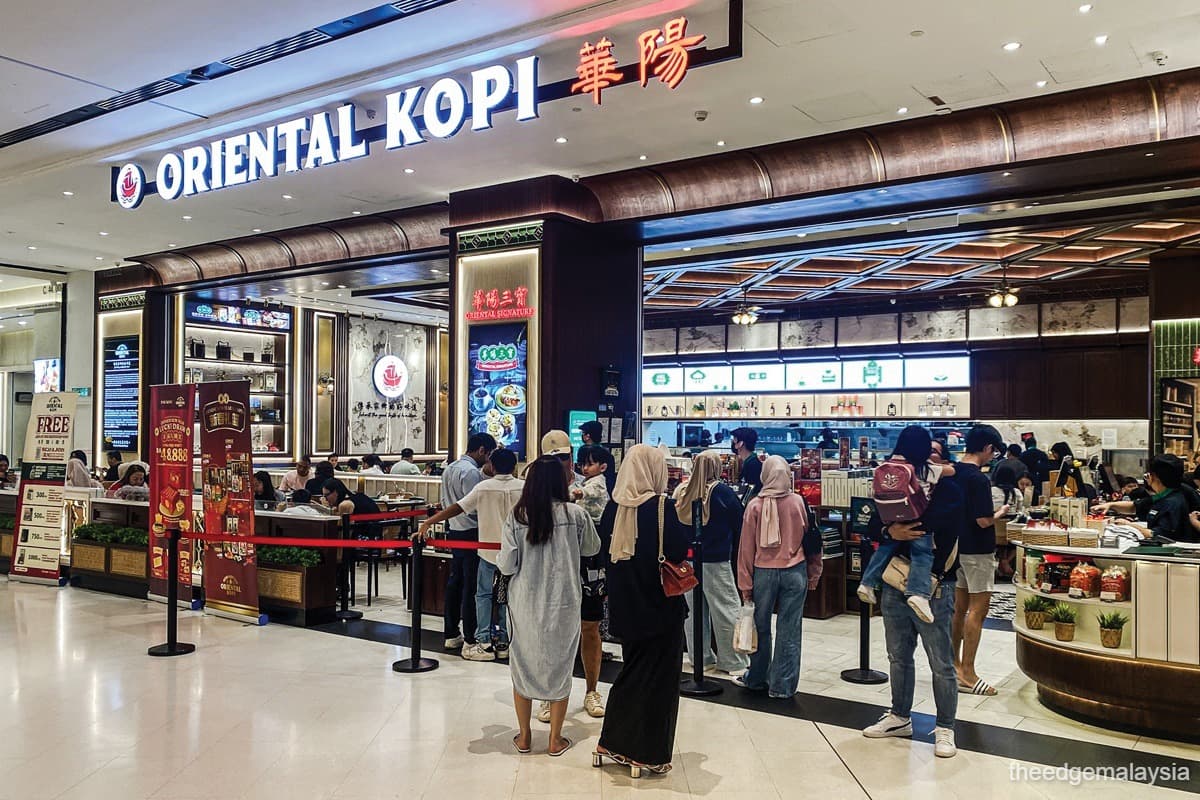
THE Ace Market-bound café operator Oriental Kopi Holdings Bhd (KL:KOPI) has garnered significant attention within the investing community due to its robust financial performance in the first four years of operation.
Since the opening of its outlet in Johor in 2020, the food and beverage player has seen its profitability increase significantly. Supported by a network of 20 cafés across Malaysia and one in Singapore, the company reported a net profit of RM43.13 million for the financial year ended Sept 30, 2024 (FY2024), more than doubling the RM20.03 million recorded in FY2023.
In addition to its café operations, Oriental Kopi sells in-store packaged coffee, tea and other food products such as spreads, pastries, instant noodles and seasonal items like mooncakes.
“From the start, we insisted on creating a restaurant [chain] for all races, which is very important to us. We want to promote Malaysian cuisine not only locally but also internationally,” Oriental Kopi co-founder and managing director Datuk Calvin Chan Jian Chern tells The Edge in an interview.
Under its initial public offering (IPO), Oriental Kopi issued 418.1 million new shares — 60 million shares for the Malaysian public, 20 million shares for eligible individuals and 338.1 million shares for selected investors. The public portion of the IPO has been oversubscribed by an impressive 60 times.
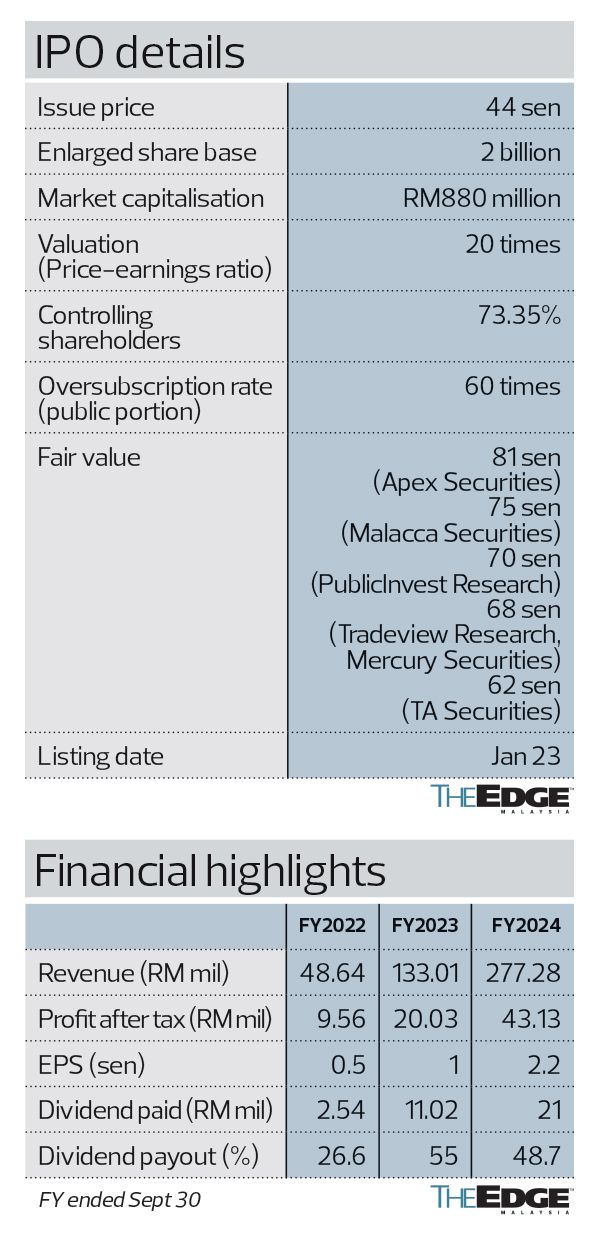
The company is expected to have a market capitalisation of RM880 million upon listing, valuing it at about 20 times its FY2024 earnings. Of the IPO proceeds, RM75.78 million has been earmarked for working capital; RM53.68 million will fund the establishment of a new head office, central kitchen and warehouse; and RM36.4 million is allocated for the expansion of cafés within Malaysia. The company plans to open seven new outlets in 2025 and an additional three in 2026.
Oriental Kopi has secured halal certification for 13 outlets and is working towards certifying all existing cafés, with the process expected to be completed by 2Q2025.
“According to the Jakim halal requirement, we cannot just directly apply for halal certification before opening a new outlet. Once we open the new outlet, we will submit the halal application as soon as possible,” Jian Chern explains.
Apex Securities, which has assigned the highest fair value of 81 sen per share for Oriental Kopi, says the 20 times price-earnings (PE) ratio based on FY2026 core earnings per share of four sen — which represents a 30% premium compared to selected peers in the fast-moving consumer goods (FMCG) retail services segment — is justified given the group’s growth prospects and the precedent set by Oldtown Bhd, which was privatised in 2017 at an acquisition PE multiple of 23.6 times.
Having demonstrated an impressive core net profit performance from FY2022 to FY2024 — with a three-year compound annual growth rate (CAGR) of 112.4% — Apex anticipates further growth for Oriental Kopi. This will be driven by operational cost efficiencies, aggressive café expansion across Malaysia, increased sales of house-branded packaged foods and expected same-store sales growth of 13% in FY2025 and 42% in FY2026.
Apex also highlights that the outlet at KLIA2’s departure and arrival areas is one of the group’s top-performing locations. “With the higher tourist arrivals, Oriental Kopi could potentially capture larger market share on the in-house branded consumable goods via the purchase of goods from the store as souvenirs,” it says in a Jan 10 note.
Despite not yet having an established central kitchen, Oriental Kopi’s FY2024 net profit margin already stood at 15.6%. Apex believes the establishment of a central kitchen will unlock significant growth potential for the group.
Mercury Securities projects the company’s net profit margins to remain strong at 15% to 16%, driven by efficiency gains from the new central kitchen, higher-margin FMCG sales and periodic pricing adjustments to mitigate rising raw material and wage costs.
“Unlike competing peers operating more than 100 outlets (including franchising) such as OldTown and PappaRich, we understand Oriental Kopi only intends to open 40 to 50 owned-operated outlets in Malaysia eventually, mainly targeting high-traffic areas such as shopping malls,” the report explains.
According to Jian Chern, this approach underscores the group’s emphasis on quality control and customer experience.
“We want to ensure consistency in our products and services, which is why we reiterate our commitment to not franchising. The stability of my restaurants is very important for us. We are not simply aiming to open so many outlets if we cannot control the quality and good services. Instead, we are taking a step-by-step approach,” he highlights.
With a relatively low capital expenditure of RM2.5 million to RM2.8 million per new outlet, Malacca Securities notes that new locations typically achieve a payback period of just 10 to 12 months.
The group maintained a healthy balance sheet with a net cash position throughout FY2021-2024. As at end-September last year, Oriental Kopi’s net cash position stood at RM59.4 million or 2.97 sen per share.
Oriental Kopi plans to distribute 30% of its annual profit as dividends.
Following its listing, United Gomax Sdn Bhd will hold 73.35% of Oriental Kopi. The shareholders of United Gomax are Jian Chern (57.53%), executive director Chan Yen Min (21.23%), executive director Koay Song Leng (14.89%), head chef Ho Poh Chian (3.19%) and retail operation manager Koay Chor Leng (3.16%).
Besides Jian Chern, Yen Min and Koay are also the co-founders of Oriental Kopi.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.