

This article first appeared in The Edge Malaysia Weekly on September 16, 2024 - September 22, 2024

IHH Healthcare Bhd (KL:IHH), which has a dual listing on both sides of the Causeway, has seen earnings rebound from the pandemic-induced hit in the financial year ended Dec 31, 2020 (FY2020).
For FY2023, the healthcare group’s bottom line nearly doubled year on year (y-o-y), bolstered by a RM981.42 million gain from the sale of IMU Health Sdn Bhd (RM862 million) and Gleneagles Chengdu Hospital (RM116.5 million).
From only RM288.9 million in pandemic-hit FY2020, its net profit rose to RM1.86 billion in FY2021. Despite declining to RM1.55 billion in FY2022, the one-off gains pushed its net earnings to a record high of RM2.95 billion in FY2023. Excluding the exceptional items, its FY2023 net earnings would have been lower y-o-y at RM1.28 billion on the back of higher net finance costs and lower exchange gains.

Based on The Edge Billion Ringgit Club (BRC) awards methodology, IHH’s risk-weighted three-year net profit compound annual growth rate (CAGR) for the period under review from FY2020 to FY2023 came in at 93.65% — the highest among all the companies with a market value of over RM1 billion under the healthcare sector.
In the absence of disposal gains, IHH’s 1QFY2024 net profit was down 45% y-o-y to RM767.97 million from RM1.39 billion in the same quarter a year ago.
The disposal gains were distributed to its shareholders via a special dividend of 9.6 sen per share, bringing the FY2023 total dividend to 18.6 sen dividend per share, versus seven sen per share for FY2022.
Worth noting is that IHH has improved its dividend policy, with a higher payout ratio of not less than 30% of its profit after tax and minority interest (excluding exceptional items) from 20% previously.

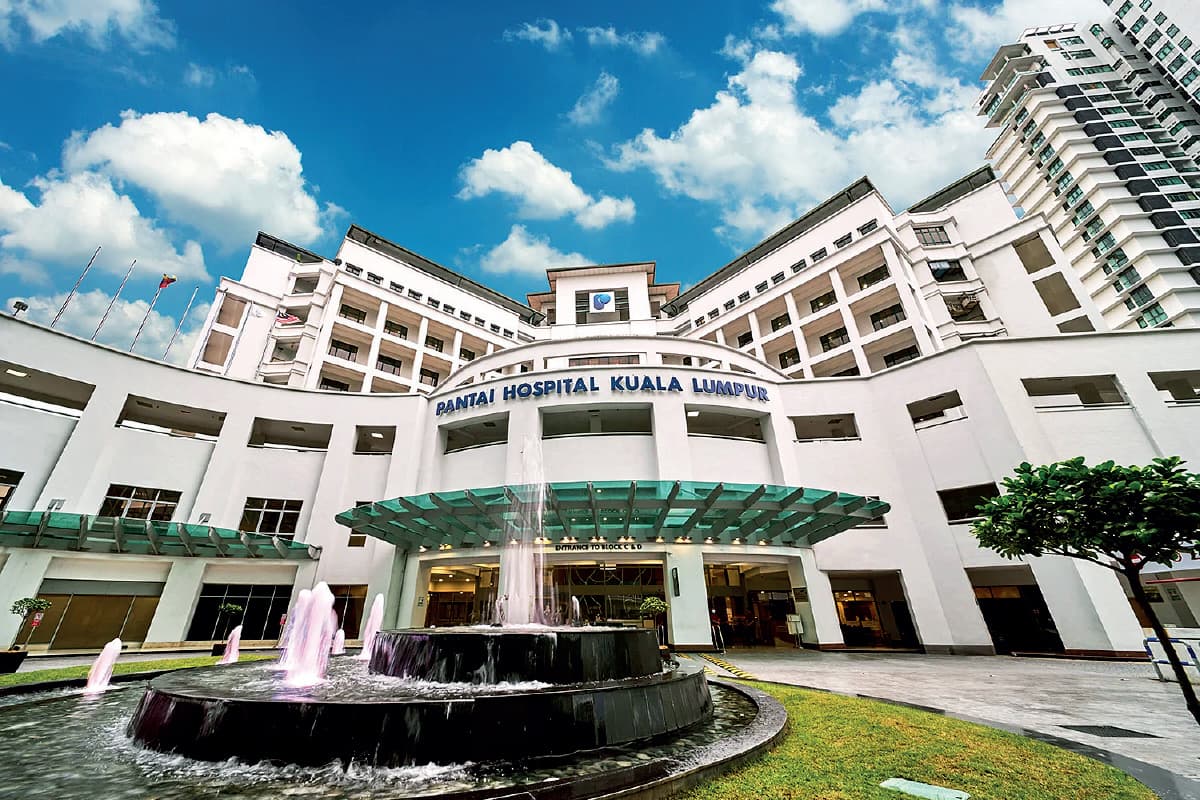
Operating more than 80 hospitals with over 12,000 operational beds in 10 countries, including Malaysia, Singapore, India, China, Hong Kong and Turkey, IHH is Asia’s largest hospital operator by market value. Its brands include Acibadem, Mount Elizabeth, Prince Court, Gleneagles, Fortis, Pantai and Parkway.

Most of the analysts are bullish on IHH’s prospects, with 18 “buy” calls and four “hold” for the group at the time of writing. The consensus target price is RM7.38, representing a 17.1% upside against its closing price of RM6.30 on Aug 27.
In an Aug 9 note, CIMB Securities said IHH’s current valuation is compelling, backed by its long-term earnings resiliency and robust growth potential. The stock was trading at 11 times CY2025 EV/Ebitda, which is a discount of 25% and 34% to its five-year historical mean and regional industry average EV/Ebitda respectively. The research firm believes that IHH is well positioned to capitalise on rising demand for private healthcare.
IHH is working to add close to 4,000 beds by 2028 to its existing hospital facilities in Malaysia, India, Türkiye, Europe and Hong Kong, giving it a total added capacity of 33%.

“This would translate into a decent organic growth for IHH at a CAGR of 5.8% over FY2023-FY2028. The majority (around 80%) of this bed capacity expansion is concentrated in India (+1,860 beds) and Malaysia (+1,300 beds) due mainly to relatively stronger growth prospects, and the high bed occupancy rates at 70% in India and 72% in Malaysia in FY2023,” CIMB Securities noted.
Last May, IHH management shared that the group is looking for potential mergers and acquisitions in Indonesia and Vietnam. Early this year, the group completed the acquisition of Timberland Medical Centre in Kuching, Sarawak, for RM245 million, expanding its footprint to East Malaysia.
Commenting on the outlook, IHH, in its latest financial statements, said: “Despite the strong underlying demand for quality healthcare services, the group is cognisant of the cost pressures arising from sustained inflation, rising energy prices and higher staff costs. These challenges are not unique to the healthcare industry.
“The group is confident that it would be able to maintain a tight rein on costs and leverage operational synergies from its international network to achieve cost savings while, at the same time, ensuring the delivery of high-quality care and value to its patients.”
Mitsui & Co Ltd, through MBK Healthcare Management Pte Ltd, holds a 32.8% stake in IHH, being its largest shareholder. Khazanah Nasional Bhd, via Pulau Memutik Ventures Sdn Bhd, owns a 25.73% equity interest in IHH, while the Employees Provident Fund holds 11.33%.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.