


A major shift introduced by the Inland Revenue Board (IRB) through the Self-Assessment Stamp Duty System (Sistem Taksir Sendiri Duti Setem or STSDS) will come into effect on Jan 1, 2026, whereby taxpayers are required to assess and pay stamp duty online directly via MyTax under the digital-first model.
This will kick-start the first stage of Malaysia’s stamp duty system transition from an official assessment regime, in which the tax authorities determine the duty payable, to a self-assessment system comprising three phases.
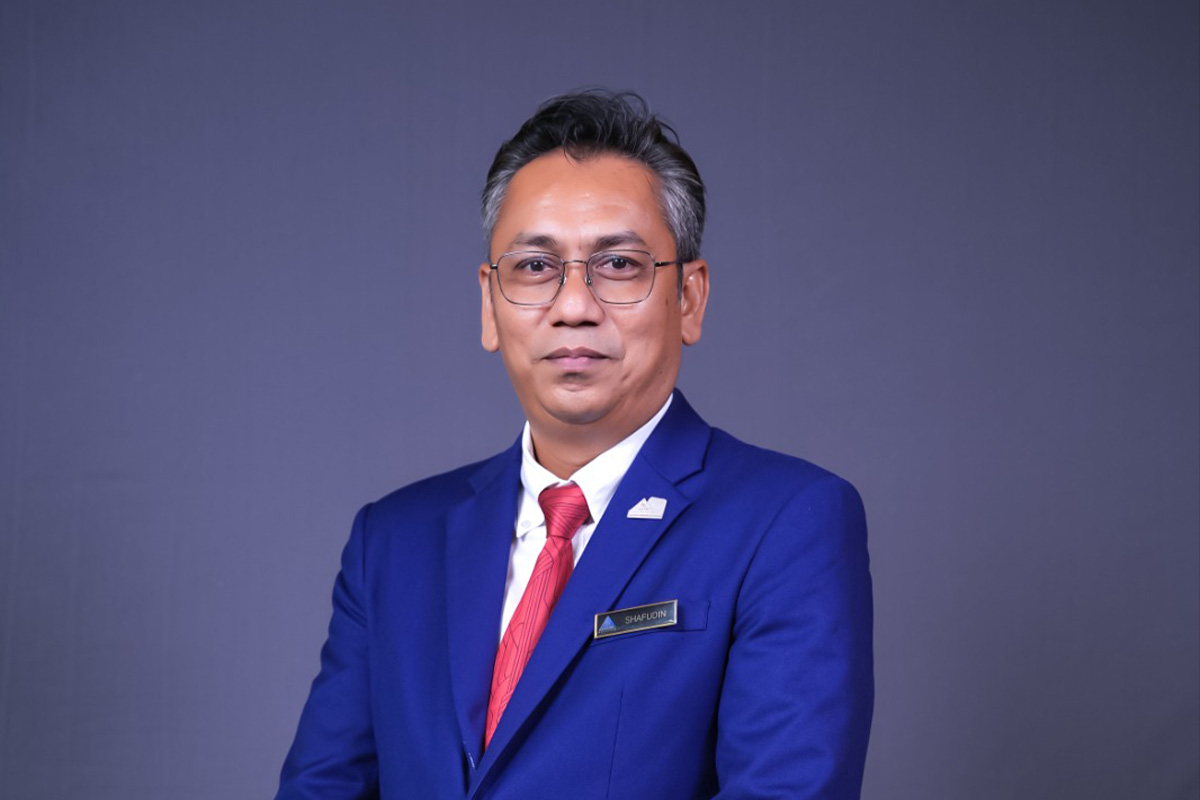
“This is consistent with Malaysia’s recent policy direction towards digitalisation, self-assessment and stronger compliance rather than raising headline tax rates. It aligns with other measures, such as e-invoicing and enhanced audit frameworks, intended to broaden the tax base, improve administrative efficiency and reduce under-reporting. The move shifts transactional friction into upstream digital compliance and enforcement,” says Shafudin Yacob, Director of Stamp and RPGT Operation Department, HASiL.
The STSDS will be rolled out digitally in stages, with the first phase starting on Jan 1, covering rental and lease agreements, general encumbrances and security documents. The second phase will begin on Jan 1, 2027, to include property transfer documents (without JPPH valuation). The remaining dutiable instruments will form part of the STSDS in the final phase beginning Jan 1, 2028.
The government first announced plans for the phased implementation of the STSDS in late 2024, with proposed amendments to the Stamp Act 1949 and relaxed tax collection laws as part of tax administration reforms introduced when the 2025 budget was tabled. The legal changes gave statutory power to taxpayers to self-assess stamp duty, calculate and declare duty owed, move stamping processes fully online and strengthen penalties and audit powers.
Under the STSDS, taxpayers must file a stamp-duty return via MyTax. Once the return is filed, it is deemed an assessment unless the collector elects a formal assessment. Duty payers are subject to all obligations, including record-keeping, filing and making payment. Any failure to comply will expose them to increased fines and audit risk.
“The STSDS essentially affects the same dutiable instrument types that are already subject to stamp duty. The only difference is that the duty calculation and filing will now shift to the taxpayers,” Shafudin says.
With the STSDS, the government aims to increase compliance by reducing the occurrence of unstamped and under-stamped documents. It is also hoping to speed up collection by making duty payable when the return is filed. The new regime will reduce administrative costs and manual processing while enabling targeted audits using digital records.
“The expected impact for the government will be improved revenue collection and fewer manual assessments, although the exact revenue contribution will depend on compliance behaviour and audit intensity. The legislation also raises penalties to deter late stamping, which should increase receipts from late penalties as well,” Shafudin says.
There are several key benefits for the shift towards STSDS. For one, it will move stamp duty administration to a streamlined digital process, with complete assessment and payment conducted through MyTax without having to wait for assessment notices. It offers greater control for businesses, as users are able to manage their own submissions, valuations and payment timing, thus reducing bottlenecks and improving compliance oversight.
Shafudin highlights that the new regime allows faster turnaround times with reduced dependency on manual review, contributing to quicker completion of property, share transfer and commercial documentation.
Moving to the STSDS will enhance transparency and accuracy in Malaysia’s stamp duty administration, with clear rules, guided digital forms and audit trails helping to prevent errors and reduce disputes. It also raises Malaysia’s competitiveness, as the system is modelled after similar processes used in countries including Singapore, Hong Kong, the UK and Australia. With seamless integration into MyTax, the new regime provides a single platform for income tax, e-Invoice and now stamp duty, making it easier for businesses to manage tax obligations.

“While Malaysia’s STSDS moves stamp duty administration toward the digital, self-service model used in Hong Kong and Singapore, it differs slightly from Australia’s state-based model. In Malaysia, STSDS administration is centralised nationally,” Shafudin says.
He points out that the experience in other jurisdictions has shown clear benefits: faster processing, fewer physical stamps and better audit trails.
In Hong Kong, the e-stamping service, involving the instant issuance of stamp certificates online for property transactions, tenancy agreements and other dutiable instruments, was launched on Aug 2, 2004, under the Stamp Duty (Amendment) Ordinance 2003. The island city’s experience was a successful one once the system matured, resulting in faster stamping, electronic proof and reduced need to visit tax counters. While the early years required stakeholder education, the implementation success was attributed to clear rules and reliable service.
In Singapore, the Inland Revenue Authority of Singapore e-stamping system, allowing online stamping and certificate retrieval, was introduced around 1999 before being significantly updated with a new public e-stamping site in 2010. The experience down south was one of high adoption and low friction, with its success tied to long lead times, strong user experience and good support for businesses and intermediaries.
In Australia, stamp or transfer duty is a state responsibility. Many states support online lodgement and self-assessment workflows for licensed conveyancers or agents. Australia also uses national e-conveyancing platforms (PEXA) to digitise settlements and title lodgement. Electronic conveyancing and digital lodgement were rolled out progressively in New South Wales and other states, which began going digital in the mid-2010s. E-conveyancing was implemented from 2014 onwards. Since then, the state online duty portals have continued to evolve.
The Australian experience has delivered major gains in speed and fraud reduction where PEXA/e-conveyancing is used, but risks include vendor concentration due to PEXA’s dominance, interoperability challenges and occasional outages. State rule fragmentation also makes cross-jurisdiction transactions complex, although phased implementation has helped alleviate this.
“Cross-jurisdiction lessons show that the benefits of e-stamping and self-assessment are real. Still, international experience also suggests that success is determined by the level of user readiness and integration. When platforms are integrated with conveyancing systems, property registries, banks or human resources systems, adoption and compliance are smoother. Early guidance and calculators also help reduce mistakes. Malaysia is likewise learning from overseas experience that phased rollouts with solid support will make the transition smoother,” Shafudin says.
However, operational risks do exist even with detailed planning. These include computer outages, vendor monopoly and interoperability issues such as those seen in Australia’s PEXA system, and initial disputes over valuation or duty treatment. The government must provide fallback plans and clear dispute pathways, he adds.
In any case, digital platforms succeed when deadlines, procedures and user flows are clear, and when they are integrated with common business processes such as human resources, property registries and e-contracts. Another success factor lies in the availability of transitional relief and adequate communication. Where governments have offered phased roll-outs and technical support, compliance improved with limited disruption; where change was abrupt, businesses reported operational challenges.
Malaysia has adopted a phased roll-out (2026-2028) as the main transitional mechanism in the shift towards the STSDS, giving affected sectors staggered implementation windows. Specific reliefs were made available, with guidance and transitional measures provided in the budget proposals and IRB materials. The tax authorities have also published guidance and technical notes, with penalty remission windows announced in parts for certain items during the transition years.
Following that, full obligations will begin on Jan 1 for Phase 1 instruments, and the Stamp Act now contains higher penalties for late stamping. The effective grace period is therefore limited to the stated phased start dates, plus any temporary informal leniency that the IRB may announce in future. Businesses should assume no lengthy blanket grace period beyond the phase dates and should prepare to comply from those effective dates.
“With the new year drawing near, businesses, legal professionals and property stakeholders are advised to start registering for MyTax and familiarising themselves with the new STSDS workflow,” Shafudin says.
For updates and detailed guidance, visit HASiL’s official website:https://www.hasil.gov.my/en/stamp-duty/sistem-taksir-sendiri-duti-setem-stsds/