

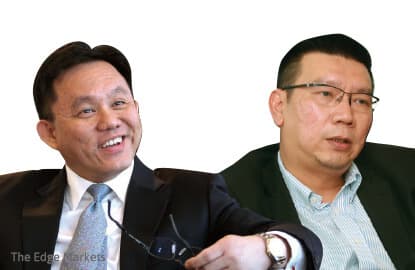
A well-managed credit profile is instrumental in helping individuals achieve their major life goals, such as buying their dream home or kick-starting their business. Without a good credit score, they run the risk of having their loan applications rejected.
According to Eric Chin, CEO of credit reporting agency CTOS Data Systems Sdn Bhd, the loan approval rate in the country is on the decline because Malaysians are generally unaware of their credit standing.
“When people apply for a loan and get rejected, oftentimes they do not know the reason for it. In fact, they should know the likelihood of getting their loan approved even before they apply for any type of financing,” he says.
He adds that Malaysia’s household debt stood at RM1.03 trillion, or 89.1% of its gross domestic product (GDP), in May. “While the situation is not too alarming, as the debts are going to quality assets, it does raise concerns about the level of awareness and education among Malaysians in terms of good credit management.”
Wong Kum Cheong, CEO of Credit Bureau Malaysia Sdn Bhd (CBM), says good credit management is increasingly important today as credit facilities are no longer a luxury. “Nowadays, there are a lot of high priced items that require you to save up for a long time if you wish to pay for it in cash. It does not help that these items, such as a car, computer or smartphone, are now necessities. Thus, many resort to credit facilities.”
By maintaining a good credit history, consumers can get better deals from credit grantors, he adds. “For many years now, Bank Negara Malaysia has been working with banks to move towards “risk-based pricing”, which means those with higher credit risk should be charged higher interest rates while those with lower credit risk should be entitled to lower interest rates. While not all banks practise this, competitive banks have implemented it for housing mortgages, auto hire-purchase, credit cards and personal loans.”
Consumers can walk into any of Bank Negara’s branch offices to ask for a free copy of their credit report. However, the central bank’s report only provides information taken from the Centralised Credit Reference Information System (CCRIS). For other types of information, such as legal history, trade references and advice on how to improve their credit scores, they can turn to private reporting agencies, such as CTOS, CBM and RAM Credit Information Sdn Bhd (RAMCI).
CTOS provides information on legal actions, cases statuses and business exposure (individual’s directorships and shareholdings in Malaysian incorporated companies and businesses). By using the company’s app or visiting its website, consumers can get a copy of their MyCTOS Score, which gives them a better picture of their credit standing.
These MyCTOS Score reports cost RM25 each. But for a limited time, CTOS is giving away 100,000 reports. At time of writing, there were only 38,000 free reports left.
CTOS works closely with its information providers to ensure that its reports are as accurate and up-to-date as possible. Chin says consumers have the right to contact the company and notify it of any errors or inaccuracies.
“Consumers can contact us and we will verify the information for them. There is also a section in our report called “subject’s comments”, which allows them to have a say,” he adds.
“For example, if the report says the individual is borrowing some sort of loan from a bank, but they are not, this is where they can address that problem for our subscribers to take note of.”
Similarly, CBM offers MySCoRE reports for RM10 each. Banks use this report when assessing a loan applicant’s creditworthiness. The credit reporting agency relies on sources such as CCRIS and the Companies Commission of Malaysia to ensure the accuracy of the information. It also uses its own algorithms to verify any data its system collects.
CTOS — in collaboration with its first strategic partner, Alliance Bank Malaysia Bhd — is offering individuals with a good credit history a special fixed deposit or Term Deposit-i rate of 3.70% per annum (the regular rate is 3.90%) for three months placement (for a minimum deposit of RM25,00). They also get rates as low as 4.99% per annum with Alliance CashFirst Personal Loan (normal rate is 7.68%); up to a RM200 cash voucher when they use their Alliance Bank credit card at least three times; and 0% balance transfer for up to 12 months with minimum transfer amount of RM3,000.
“We are looking to work with other partners, such as telecommunications, electronic and household product providers, to reward people with good credit scores to motivate them to continue their good conduct. Hopefully, we can announce such collaborations in the first quarter of next year,” says Chin.
Improving your credit rating
Once consumers get their latest credit score, they can take steps to maintain or improve it. At the top of this list is paying any outstanding credit owed on time, says Chin. “Being timely with your payments is key. Every credit grantor, lender and bank out there appreciates a borrower with a good payment track record as it shows that the person has good credit habits.”
Wong warns that late payments may have a long-term effect on debtors, even if they are only a few days late. “You may feel that it does not matter much. Your bank may even tell you that it is alright, that there is no penalty, and that it will sweep it aside once the money is banked in. But they will still report it to the CCRIS as late payment. This will reflect negatively on your credit score,” he says.
Having a good relationship with your banker is important in helping the bank know its borrowers better as it is required to implement the Know Your Customer (KYC) process, says Wong. The more information the customer discloses to his banker during the process, the more assistance the bank will be able to provide. This relationship is especially important when debtors get themselves into a bad financial situation, he adds.
“A lot of people do not answer calls from the bank when they are in some sort of financial problem. Somehow, they feel that if they do not talk to the bank, it cannot go after them. This cannot be further from the truth. Do you know what happens when you cannot be contacted and do not turn up in court? The banks will get a judgment in default,” says Wong.
“What consumers need to know is that there are ways to resolve this. Try to negotiate with the bank as it does not want to have these defaults in their books either. Ask it to either stretch the payments or reduce the rates, if possible. If the bank cannot help, reach out to AKPK (the Credit Counselling and Debt Management Agency). You will still need to pay off your loans, but at least you will receive some kind of assistance.”
Wong says consumers must not only think of their existing cash flow when they are considering a loan but also factor in their cash flow in challenging times. “Let’s say you are thinking of buying a Honda Accord.
While you are able to afford it with your monthly income, what will happen if you do not get an increment or bonus — or worse, lose your job?
“Under these kinds of circumstances, should you stretch your money to pay for the car, or should you just buy a Honda Civic, which will have less impact on your cash flow? You should allow yourself some wiggle room.”
Consumers should also be prepared for worst-case scenarios and have enough savings for at least four months to pay their outstanding loans. This is to avoid late payments, which will be listed in their credit history. In Malaysia, borrowers who are late for more than three months are considered delinquents.
Wong advises consumers to avoid taking on too much credit. “What we have observed is that 70% of those who are in financial trouble have five or more credit facilities. They may consist of a housing loan, a car loan and three credit cards. It is very difficult to make payments to all these different facilities at the same time. If you have more than five credit facilities, you have a higher chance of getting into trouble, so be extra cautious if you already have four facilities,” he says.
He adds that credit facilities should be used judiciously and only for the right purposes. Credit card debt, for example, should be cleared off as soon as possible.
“If you cannot pay it off in six months, do not charge it to a card. Do you know that if you cannot pay it off in six months, the price of the item goes up by 10%? So, if you are unable to pay it off in a year, it is already 20% more than what you would have paid. Therefore, in the next four to five years, you could end up paying double the initial amount,” he says.
Areas of concern
While Malaysia’s household debt is among the highest in Asia, Wong says this is not a cause for concern as it is mostly caused by Malaysians taking up new mortgages to invest in properties in the current low interest rate environment. There is also household debt in other countries as governments reduce interest rates and implement regular quantitative easing. Because of this, banks have had to actively market and offer loans to keep generating profits.
In fact, several reports say hire-purchase loans make up a high proportion of Malaysians’ total debt. “In the UK and the US, housing mortgages make up a large portion of those debts — about 75% to 90%. In Malaysia, mortgages only account for about 60%.Here, auto loans account for 15% to 20% of debts versus 7% in the US and 8% in the UK,” says Wong.
He adds that bankruptcy cases reached a peak in 2014, but still remain high today with an average of 1,500 people going bankrupt every month. According to the Department of Insolvency’s statistics, 97,215 people were declared bankrupt between 2012 and September this year, with Selangor ahead of the other states with 27,269 cases.
However, this is not an absolute indicator that Malaysians are bad in dealing with credit. “The number may be rising because of Malaysia’s growing population and more individuals coming into the banking system. Last year, the number of bankruptcies was 22,000. But this year, we are expecting slightly less, perhaps 18,000 to 19,000 cases,” says Wong.
Based on the information on two million individuals that has been scored by CBM, about 40% are in the top three credit grades (AA, BB and CC). These individuals have a good credit history and are sought-after clients by the banks. Of the top scorers, 36% are above 45 years old while 6% are between 18 and 25. But 20% of the database consists of moderate credit scorers, with grades between DD and FF (who repay their loans, but may be late from time to time) and 9% with poor credit grades of GG to JJ (frequent late payments).
“The top scorers are mostly above 45 years old because they have created a good credit history over the years. They are already at the point in their lives where they have stable and sufficient income, are generally more disciplined in making payments and rarely take on new loans,” says Wong.
The unscorable or “young to bureau” scorers are responsible for 19% of the scores, while the remaining 12% are already in a state of default. “Defaults do not mean that these people have run away and are hiding from the banks. The Basel capital rules says you are considered a delinquent if you are late for more than three months. So, of the 12%, 7% got their payments rescheduled, restructured, written off or were given help by AKPK. The remaining 5% are late in their payments, half of whom are already working out a resolution with their banks while the rest will end up in legal proceedings and eventually go bankrupt,” says Wong.
CTOS’ Chin says Malaysians in general are as good credit managers as those in mature markets. “We have 15.6 million individuals on file. While we have not scored all of them, our adverse record (a track record of poor repayment history) is actually less than 5%, which indicates that Malaysians are not bad credit managers. With the proper guidance, this number will surely be reduced even further,” he says.
Scoring the unscorable
Thin-file consumers are those with a brief credit history or not enough credit accounts to generate a credit score. They could be new to the credit system or those who have paid off their loans and no longer have any records in the banking system.
Eric Chin, CEO of CTOS Data Systems Sdn Bhd, says thin-file consumers may have a hard time getting a loan from the banks as there is no way to gauge how trustworthy he is. “The banks are unsure, so they may ask to look at certain things, such as your income or a letter from your employer to verify your employment and how long you have been working. For certain type of loan facilities, they may need guarantors. That is why it is important to start building your credit track record,” he says.
CTOS is looking into a way to score thin-file consumers in its upcoming collaboration with new partners next year. This may involve looking into alternative data, including unstructured data such as one’s LinkedIn or Facebook page — a practice implemented in mature markets.
On the other hand, Credit Bureau Malaysia Sdn Bhd (CBM) offers its Alternate Score Model to score thin-file consumers. By relying on the Centralised Credit Reference Information System and Companies Commission of Malaysia, CBM will look into a thin-file subject’s credit repayment history with banks and grade them using four grades — X1, X2, X3 and X4. X1 is considered the best score while X4 is the worst.
CBM CEO Wong Kum Cheong says this model only works for individuals who have some credit repayment track record at banks, but it does not apply to those with no historical records at all. “We find that this is important because putting a thin-file subject through the normal score model does not yield accurate results. The Alternate Score Model produces a more useful result,” he says.
He adds that CBM is planning to make the grading system for the Alternate Score Model more robust by assessing a consumer’s utility data, mobile payment history and utilities payment history next. “In some places, such as Latin America, psychometric scoring has been used for the last 10 years. This involves asking questions about how you view society and assessing your integrity and honesty to determine how creditworthy you are. We will be looking into something like that as well.”
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.