


This article first appeared in Capital, The Edge Malaysia Weekly on July 6, 2026 - July 12, 2026
Renewable energy
OVERWEIGHT
KENANGA INVESTMENT BANK RESEARCH (JUNE 30): The engineering, procurement, construction and commissioning (EPCC) rollouts for large-scale solar 5+ (LSS5+) projects are expected to drive near-term order book replenishment for local solar players, given that these utility-scale projects are scheduled for commercial operations starting in 2027. Our channel checks suggest that after excluding internal EPCC execution by asset owners, the estimated unallocated EPCC addressable market stands at about RM2 billion to RM3 billion, which should continue to provide robust earnings visibility for pure-play EPCC providers through to 2028.
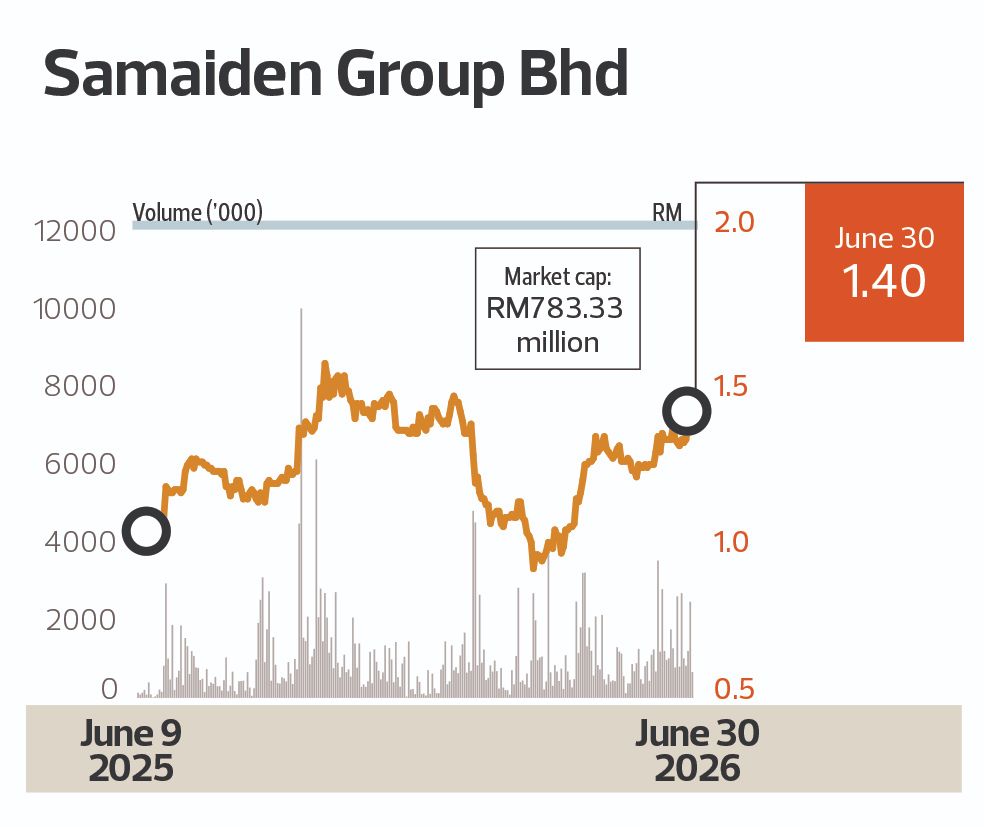
While public contract conversions have been noticeably slow, with only about 2% of total EPCC value announced so far, we expect job momentum from utility-scale solar to remain strong over the near term. This will also be supported by the preceding LSS5 cycle, where an estimated RM1 billion in EPCC contracts remains unallocated. These unawarded pipelines present highly visible contract opportunities for players like Solarvest Holdings Bhd (KL:SLVEST) (outperform; target price: RM3.45) and Samaiden Group Bhd (KL:SAMAIDEN) (outperform; TP: RM1.94), given their dominant market shares and proven execution track records in the utility-scale solar space.
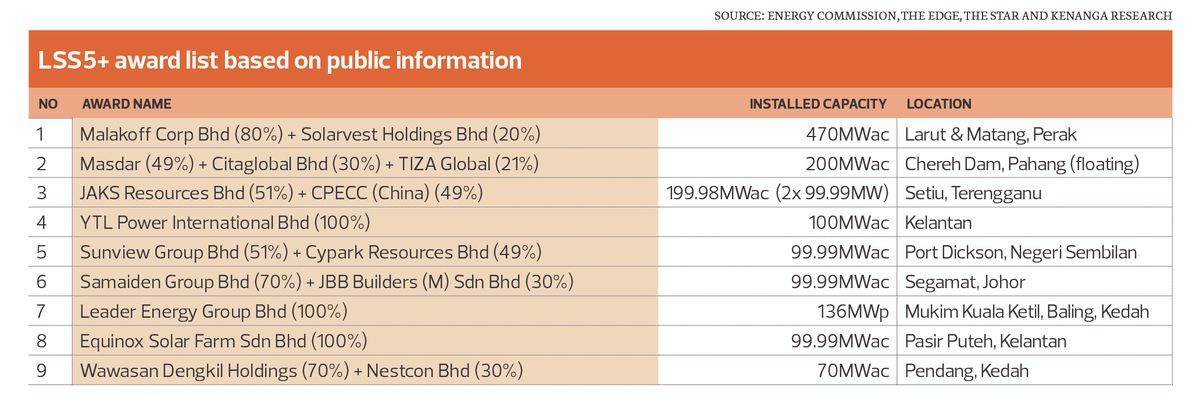
We expect near-term solar order book replenishment to remain robust, supported by module prices stabilising at 11 US cents/W. The upcoming project which we anticipate to be launched by 3QCY26, namely the 2gw LSS6 programme, serves as the next major catalyst, projected to unlock RM8 billion in battery energy storage system (BESS)-integrated EPCC opportunities. We view the Corporate Renewable Energy Supply Scheme (CRESS) positively, as it marks one of the most viable ways to address critical energy security concerns. This is mainly because a scaling 8.3gw data centre pipeline under signed electricity supply agreements risks compressing grid reserve margins from 24%, well below the mandatory 25% regulatory minimum, which is further compounded by 5.9gw of scheduled coal plant retirements by 2030. Assuming utility-scale solar paired with a standard four-hour BESS configuration, developers could absorb the 20 sen/kWh system access charge (SAC), generating RM12 billion in annual wheeling revenue for the local utility company to fund critical grid upgrades. We view this as a win-win situation for both the state and corporate off-takers, remaining the key catalyst to fundamentally transform the growth trajectory of the utility sector over the long term. We maintain our “overweight” stance on the sector, with Samaiden remaining our top pick.
HI Mobility Bhd
Target price: RM2.80 BUY
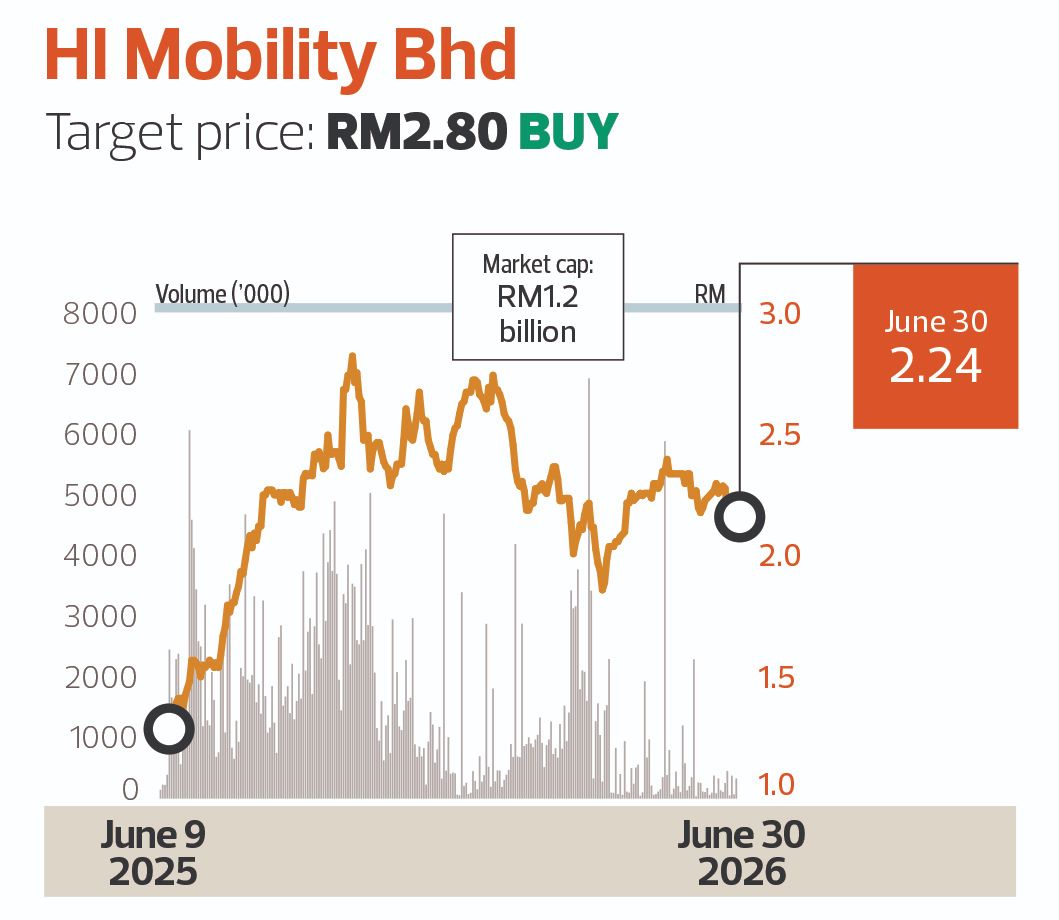
CIMB SECURITIES (JUNE 30): HI Mobility Bhd (KL:HI) reported strong 1QFY27 results, with revenue rising 51.2% year on year to RM111.5 million, driven by the maiden contribution from its commercial vehicle manufacturing, assembly and distribution segment following the completion of the Acacia Motor Services Sdn Bhd and Handal BCM Sdn Bhd acquisitions on April 8. Net profit increased 29.4% y-o-y to RM16.3 million, while core net profit rose at a faster pace of 35% y-o-y to RM17.5 million.
We expect positive synergies following the integration of Acacia and Handal BCM, which should enhance HI’s ability to bid competitively for integrated electric vehicle (EV) bus tenders requiring end-to-end delivery. Earnings visibility for the division remains strong over the coming quarters, supported by the scheduled delivery of up to 250 EV buses over the next 12 months. We maintain our earnings forecasts and “buy” rating on the stock, with an unchanged TP of RM2.80, still based on 17.8 times CY27F PER, representing a 20% premium to the public transport sector mean of 14.9 times. The group’s unbilled order book stood at RM255 million as at end-April 2026.
99 Speed Mart Retail Holdings Bhd
Target price: RM4.24 BUY
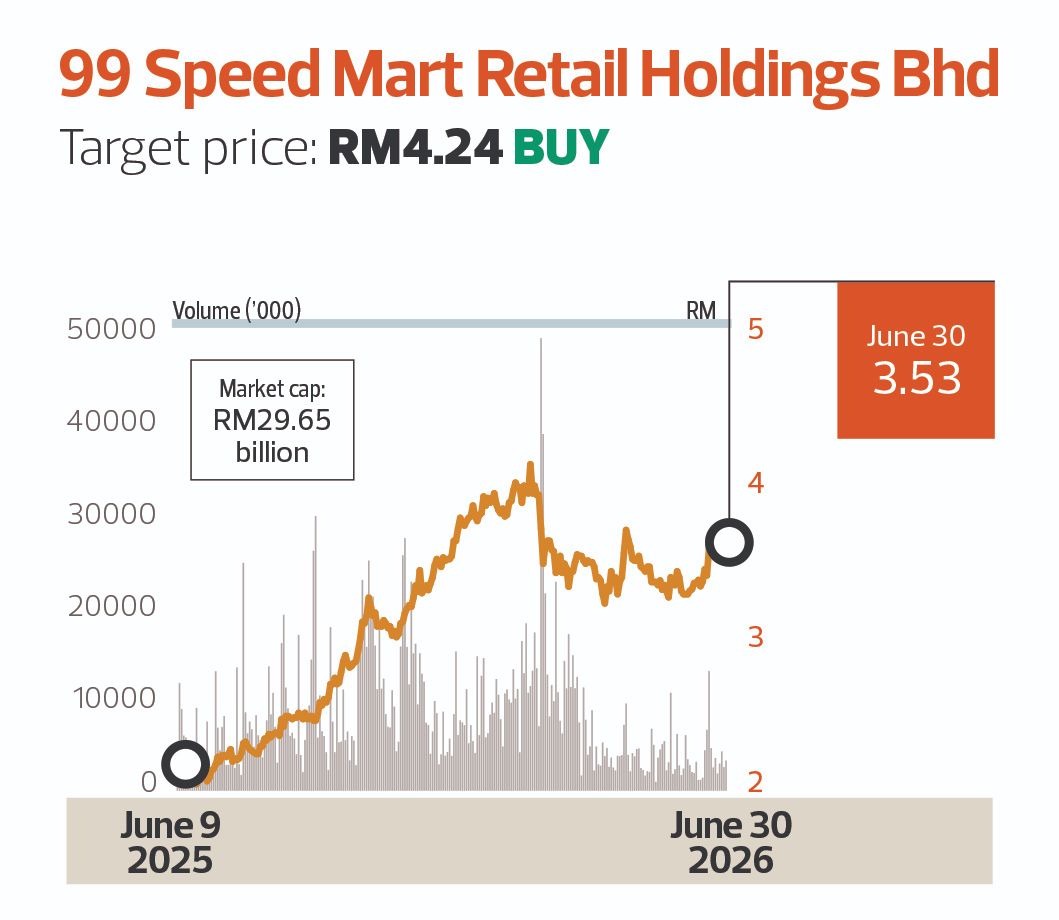
HONG LEONG INVESTMENT BANK RESEARCH (JUNE 30): 99 Speed Mart Retail Holdings Bhd (KL:99SMART) delivered strong 1Q26 results, underpinned by robust same-store sales growth (SSSG), healthy transaction growth and margin expansion. We remain positive on its earnings outlook, supported by continued store expansion, improving cost efficiencies and resilient demand for essential goods. The group is also well positioned to benefit from potential rakyat-friendly measures ahead of a possible early 16th general election, given its nationwide footprint and extensive range of Sumbangan Asas Rahmah (SARA)-eligible products. Reiterate “buy” with an unchanged TP of RM4.24 based on a DCF valuation, which implies a forward FY27 PER of 45 times.
We remain positive on 99 Speed Mart’s FY26 trajectory, supported by its resilience as a consumer staple and its competitive market position. The group is poised to sustain its earnings momentum through a steady rollout of 250 new outlets annually, leveraging its 3,089-store scale and full nationwide presence. Despite geopolitical headwinds in the Middle East, the group has not flagged any concerns on its current operations and is confident in its ability to capitalise on resilient demand for essential items.
Matrix Concepts Holdings Bhd
Target price: RM1.55 BUY
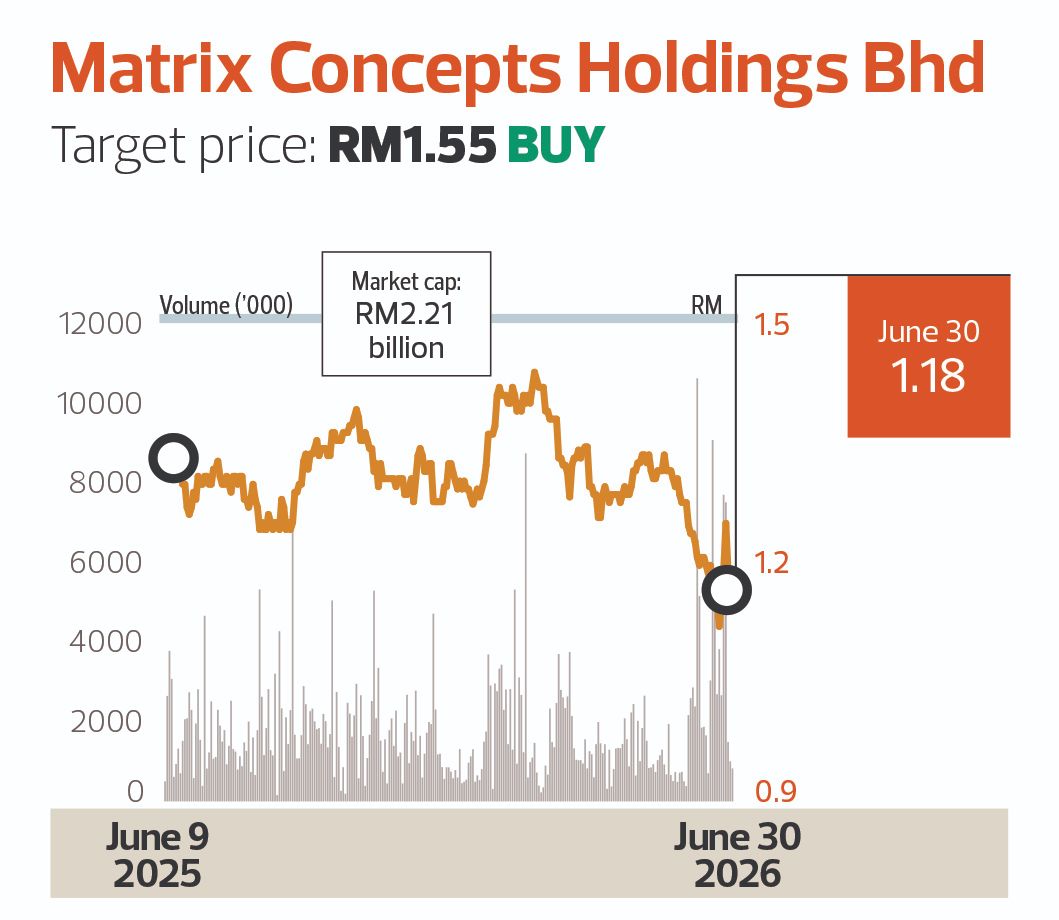
MBSB RESEARCH (JUNE 30): We believe Matrix Concepts Holdings Bhd’s (KL:MATRIX) Malaysia Vision Valley (MVV) City will continue to progress despite the current situation in Negeri Sembilan, as its long-term development is driven by structural demand for industrial and logistics properties. Besides that, MVV 2.0 is supported by substantial investments and capital commitments from multiple developers such as Sime Darby Property Bhd (KL:SIMEPROP) and Eco World Development Group Bhd (KL:ECOWLD), which should underpin its long-term development trajectory. On a side note, we believe the current (political) situation in Negeri Sembilan is unlikely to materially affect operations of Matrix Concepts, as the company has demonstrated resilience through previous changes in the state administration, with its operations remaining fundamentally intact.
New sales prospects and earnings outlook are expected to be better in FY27 following the temporary weakness seen in FY26. Our TP for Matrix Concepts is maintained at RM1.55, based on a 30% discount to RNAV. We believe the recent share price decline to a two-year low does not reflect Matrix Concepts’ underlying fundamentals. Combined with an expected dividend yield of 6% for FY27, the current valuation provides an attractive entry point for long-term investors.
Save by subscribing to us for your print and/or digital copy.
P/S: The Edge is also available on Apple's App Store and Android's Google Play.